What a Bridge Costs: Fees Take 8.5% of Loans Under £50,000
Published
6 min read
In Lendlord's latest bridging deals, of which 272 are approved for disclosure, the median fee was 8.5% of the loan under £50,000. From £100,000 to £249,999 the median fee share was 3.9%. At £250,000 and over it was 3.0%. The monthly rate sat between 1.06% and 1.1% in every band.
Price the fees in pounds before you bid. On a small bridge they can outweigh several months of interest. The monthly rate is not the line that moves.
Below: the four bands, what sits inside the fee, and a six-month cost on two loans.
Figures last checked on 30 September 2026. Deals were funded from August 2021 to August 2026. This cut is Lendlord's latest bridging deals, of which 272 are approved for disclosure.
Your own term
Read the fee line before you compare rates
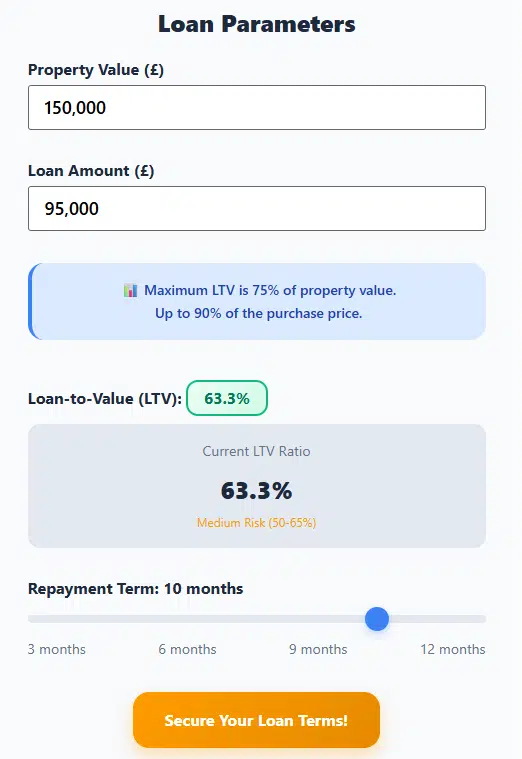
The bands below are medians. Your valuation and legal lines will differ. Put the amount in and read the fee before you accept terms.
Price a bridgeWhat each loan size actually paid
The fee share is total fees divided by the loan. Total fees here are the arrangement fee plus valuation, admin and legal. A larger loan does not show a lower monthly rate in this cut. The fee share is what changes.
On a phone, read the fee-share column first: 8.5%, then 5.4%, then 3.9%, then 3.0%.
| Loan size | Deals | Median loan | Median total fees | Fees as % of loan | Monthly rate |
|---|---|---|---|---|---|
| Under £50,000 | 41 | £39,750 | £3,440 | 8.5% | 1.1% |
| £50,000 to £99,999 | 101 | £71,250 | £3,960 | 5.4% | 1.08% |
| £100,000 to £249,999 | 102 | £130,625 | £5,165 | 3.9% | 1.06% |
| £250,000 and over | 28 | £466,192 | £13,493 | 3.0% | 1.1% |
Across the 272 disclosed deals the median loan is £94,688. Median fees are £4,510 and the median fee share is 4.6%. The median monthly rate is 1.08%. The middle half of rates runs from 1.02% to 1.13%.
A missing fee part is counted as zero. Across the 272 disclosed deals, 13 have no valuation and 32 have no legal line. In the £250,000 and over band, 12 of 28 deals have a blank part, so that row is a floor.
Exit fees appear on 2 deals and are left out. The median term is 12 months in every band. There is no split by year. These deals are not every bridge written in the country.
Where the fee actually sits
Under £50,000 the arrangement fee is 3.0% and fixed fees are £2,490. Valuation is £495, admin is £795 and legal is £1,300. From £50,000 to £99,999 the arrangement fee is 2.0% and fixed fees stay at £2,490. Valuation is £495, admin is £795 and legal is £1,500.
From £100,000 to £249,999 the arrangement fee is 2.0% and fixed fees are £2,715. Valuation is £495, admin is £795 and legal is £1,550. At £250,000 and over the arrangement fee is 2.0% and fixed fees are £2,895. Valuation is £650, admin is £895 and legal is £1,800.
Fixed fees are a large slice of a small loan. On the under £50,000 band they are 6.3% of the loan. On the £100,000 to £249,999 band they are 2.1%. The fee share on the small band is 2.2 times the mid-band share. The monthly rate barely moves. Ask for each line on its own. A single total hides a high legal estimate.
Six months on two loan sizes
On a £39,750 loan, the median fees are £3,440. Six months of interest at 1.1% a month is £2,624. Fees plus that interest come to £6,064, or 15.3% of the loan. The fees alone match about 7.9 months of the monthly rate.
On a £130,625 loan, the median fees are £5,165. Six months at 1.06% a month is £8,308. Fees plus interest come to £13,473, or 10.3% of the loan. The fees match about 3.7 months of the rate.
Run your own loan size and term before you treat these medians as your quote. For the wider rate tables, see this year's bridging rate ranges.
Interest here is the monthly rate times the loan, with nothing retained and nothing rolled. Rolled-up interest changes what you feel each month. Read how rolled-up interest changes the bill before you compare a serviced quote with a retained one.
If the exit slips, the spare month you did not budget becomes the problem. See what happens when a bridge runs past its term.
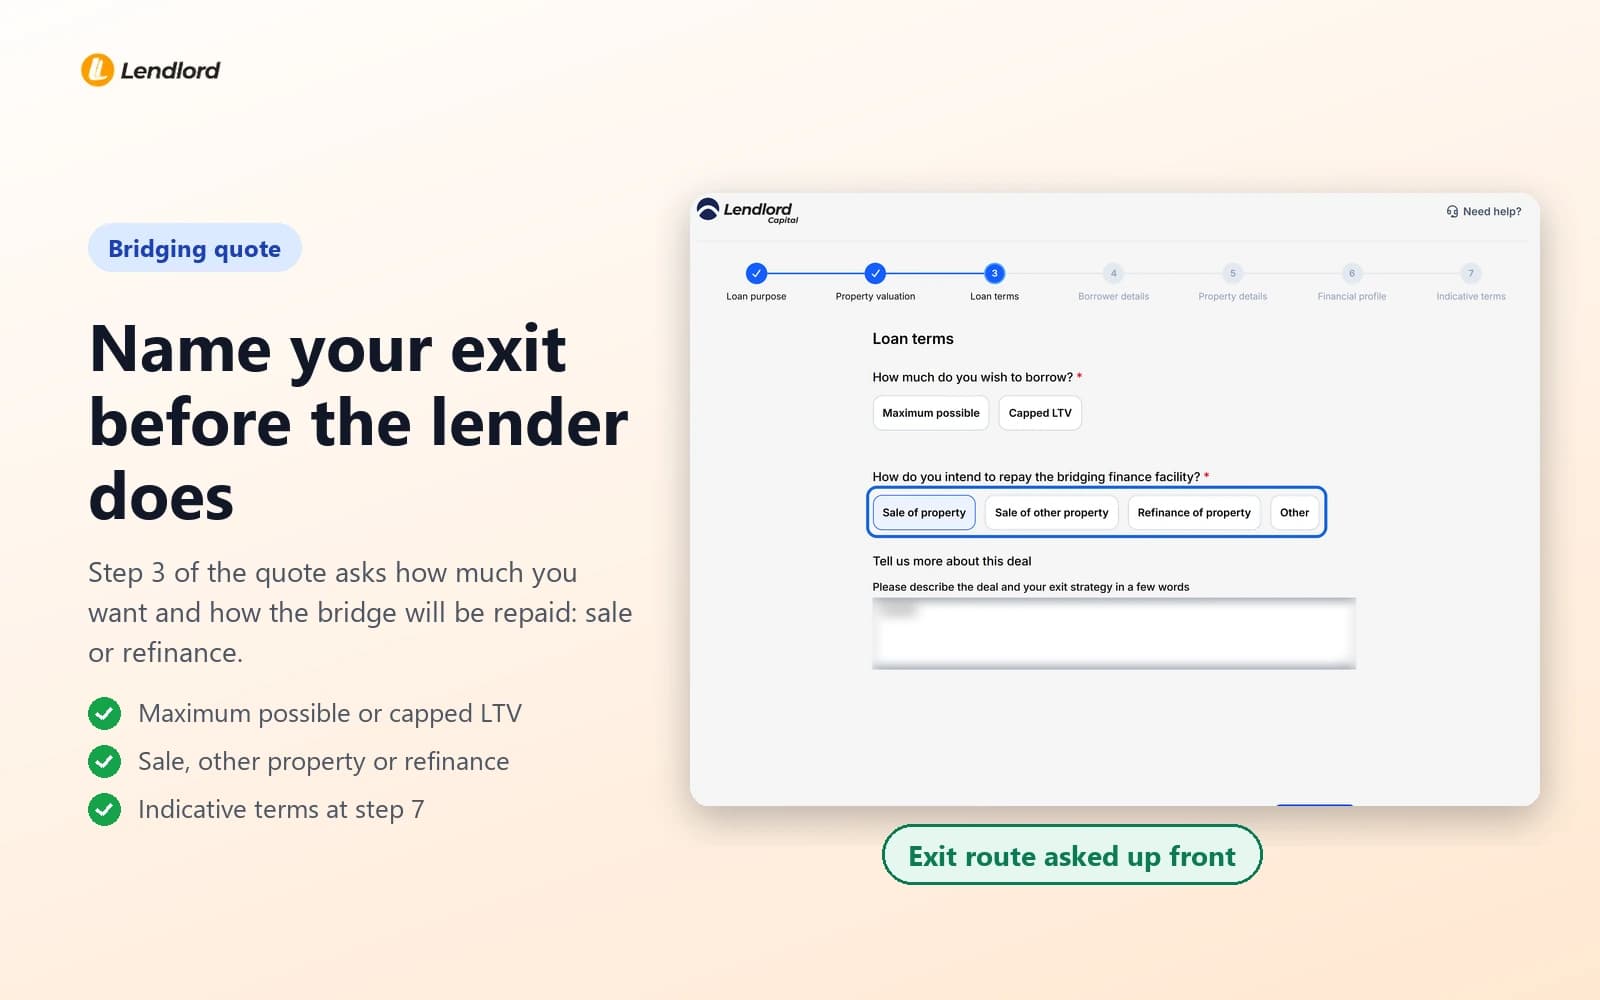
What to ask for before you accept terms
Get indicative terms while the lot is still on the catalogue. Compare the fee share with the monthly rate before you talk about the rate alone.
For the days from enquiry to funds, see how long the money takes to arrive. A fast rate quote still waits on valuation and legal work.
Property educator Jamie York, who walks through deals on Lendlord, put it like this:
…And we use Lendlord. So, Lendlord is actually a platform for property investors like you and me…Jamie York, YouTube, 9 Jan 2026 (Lendlord partner)
The video names the tool used on a deal. Your term sheet is the price.
A deal walkthrough on Lendlord
A repeat bridging customer wrote in a review on Trustpilot:
It was less than a week between signing off the offer from Lendlord and getting the cash from the loan through. Lendlord and their solicitors moved very quickly throughout the process. This is my second time working with a Lendlord on a bridge. Although not the cheapest option, speed was critical.Matt, Trustpilot review, ★★★★★ 5/5, 15 Sep 2026
One customer's experience, not a fee-table figure. Speed can be worth a higher fee.
Terms, fees and the exit
Before you accept indicative terms
Five checks on the term sheet
Do these before you treat a monthly rate as the cost.
- Put the amount and the term into the calculator linked above.
- Ask for arrangement, valuation, admin and legal as separate lines.
- Add six months of interest at the monthly rate, then set that beside the fees.
- Write the exit down, and what changes if completion slips by a month.
- Keep a spare month of interest in the budget if the refinance is not agreed.
If a fee on the term sheet sits far from your band, ask why before you proceed. A heavy refurb or a short lease can sit above these medians. The table is a check, not a cap. Speak to a bridging broker or a solicitor before you exchange.
Fee questions that change the quote
Do smaller loans cost more each month?
No. The median monthly rate is 1.1% under £50,000 and 1.1% at £250,000 and over. The mid bands sit at 1.08% and 1.06%. What changes is the fee share, from 8.5% down to 3.0%.
What is counted in the fee?
Arrangement, valuation, admin and legal. Exit fees on 2 deals are left out. A blank part counts as zero, which pulls some medians down. In the top band, 12 of 28 deals have a blank part.
How should I price my own bridge?
Use your own amount, not the all-deals median of £94,688. Add the fee lines to six months of interest, as in the worked example. Then check the exit. A broker can tell you which lender fits your exit.
Price the fees before you bid
Put the amount and the term in, then read the fee line beside the monthly rate.
Open the bridging calculator
Expert insight from Clare Harris, Bridging Loan Specialist. Director of Growth, 12+ years in loans and lending. Last updated November 2026. Price the fees in pounds before you compare monthly rates.
Official data sources
- FCA mortgage conduct rules
- RICS valuation standards (Red Book)
- HM Land Registry registration services fees
Some bridges on a home you live in are regulated mortgage business. No figures are taken from these pages. Deal figures are from Lendlord deals approved for disclosure, checked on 30 September 2026.