Two Thirds of Bridges Redeem Early. A Quarter Still Need an Extension
Published
4 min read

Across Lendlord's latest 272 bridging deals, 174 were set up to exit by refinance and 92 by sale. Of the 205 that have now repaid, 136 redeemed before the scheduled date.
That is 66% clearing early, which sounds comfortable until you look at the other 34%. Roughly a quarter of completed loans were extended at least once, and the median bridge ran 10 months against a 12-month agreed term.
So the exit works, but rarely as fast as the pitch suggests. Here is what the book shows about which exits clear, how long they take, and where the extensions cluster.
Loan book last recut September 2026. Figures cover 272 bridging deals funded since 2021, of which 205 have repaid and 67 are still running.
The six-month rule that decides when you can exit
How the latest 272 bridges were planned to end
Every case names an exit at application. Refinance dominates, which tells you most borrowers intend to keep the asset rather than trade it.
| Planned exit | Deals | Share |
|---|---|---|
| Refinance onto a term mortgage | 174 | 64% |
| Sale of the property | 92 | 34% |
| Let the property or another route | 6 | 2% |
Source: Lendlord bridging loan book, exit method recorded at application.
A refinance exit means the bridge has to leave the borrower with something a term lender will accept: a finished property, a valuation that stacks, and in most cases a tenancy. A sale exit only has to find a buyer. Different work, different risk.
Two thirds redeem before the scheduled date
Of the 205 completed loans, 136 repaid before their scheduled redemption date and 69 reached it or went past. That second group is the one worth planning for.
Separately, 52 of the 205 were extended at least once, about 25%. Extension and early redemption are not opposites: some borrowers extend and then still clear ahead of the revised date. The pattern is that a quarter of cases needed the term reopened at some point.
Plan the interest to the agreed date, not the hoped-for one. The median loan in this book ran 10 months, with the middle half landing between 7 and 12 months.
Refinance exits clear earlier than sale exits
Splitting the completed loans by planned exit shows where the slippage sits.
| Planned exit | Completed | Redeemed early | Extended | Median loan |
|---|---|---|---|---|
| Refinance exit | 128 | 70% | 20% | £87,515 |
| Sale exit | 72 | 61% | 33% | £115,125 |
Source: Lendlord bridging loan book, completed loans only. Early means repaid before the scheduled redemption date on file.
Sale exits are the larger loans and the slower ones. 33% were extended against 20% of refinance cases. A buyer's chain is outside your control in a way that a remortgage application is not.
If you are pricing a sale exit, build in the marketing period before you even reach the conveyancing. That is usually the part borrowers leave out of the term calculation.
How to set a term you will actually hit
Work back from the exit, not forward from the drawdown. Four steps that change the number you ask for.
- Date the exit event itself: practical completion of works, the tenancy start, or the day the property goes on the market.
- Add the lender's process after that date. A term remortgage needs a valuation and an offer; a sale needs a buyer and a conveyancing run.
- Check the ownership rule with your intended term lender before you draw down. Some still want six months on the title before they will refinance.
- Price the interest at the full agreed term using the dynamic bridging loan calculator, then treat an early redemption as upside rather than the plan.
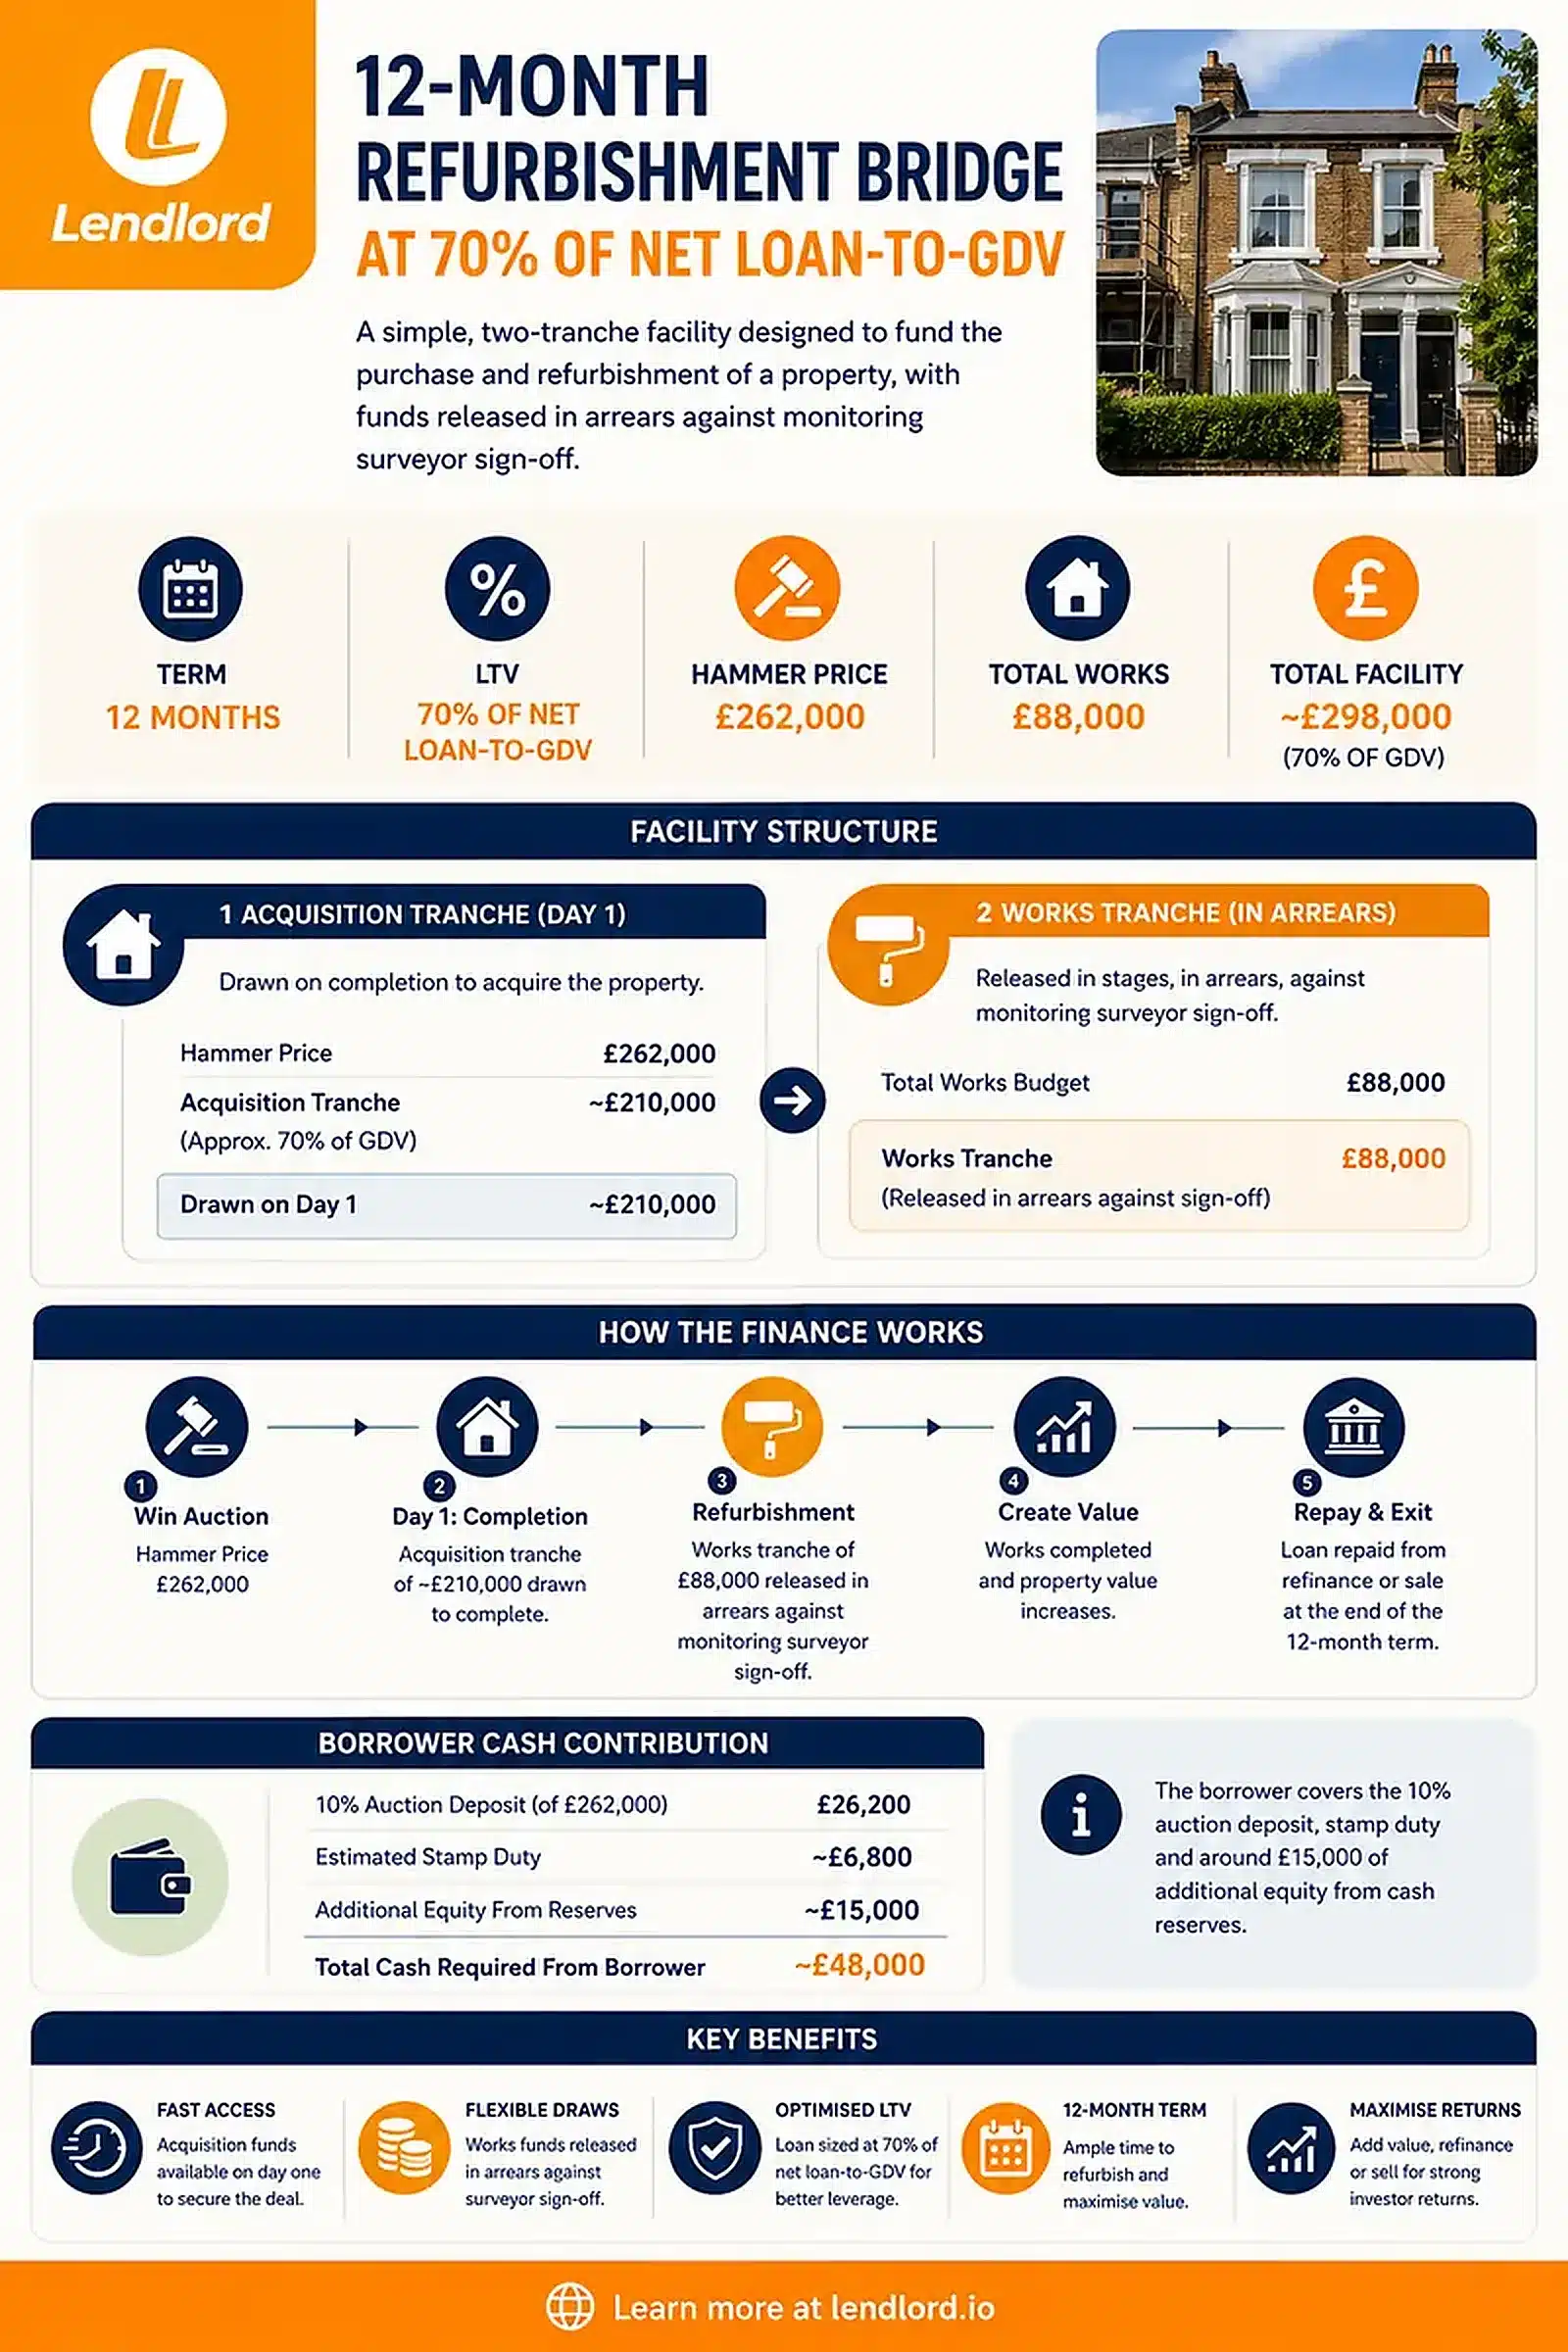
For the auction end of the book, where completion clocks drive the timetable, the breakdown of 112 auction-tagged cases covers bidding and speed. A single refurbishment deal is walked through end to end in the costs and timeline case study. Condition limits are set out in the note on lending against properties with no kitchen.
Figures come from Lendlord's bridging loan book: 272 deals funded since 2021, 205 of them repaid. Early redemption means the recorded repayment date falls before the scheduled redemption date. Term length is measured from the redemption date less the agreed term, because the recorded drawdown date is unreliable on part of the book.
An earlier internal cut reported a higher early-redemption share. That calculation used an exported term field that returned negative values on some cases, so every figure on this page has been recomputed from the dates.
Model the exit before you commit to the term
Run the loan at the term you are likely to need. Compare rolled-up against serviced interest before you apply.
Start a bridging enquiry
Expert insight from Clare Harris, Bridging Loan Specialist · Director of Growth, 12+ years in loans and lending · Last updated September 2026
Clare's reading of the extension numbers is that most of them are not distress. They are a works programme that slipped or a term lender that wanted one more document. Ask for the longer term at the start. Reopening a facility late costs more than paying a month of interest you did not need.