Will a Lender Bridge a Stoke-on-Trent Lot Under £50k?
Yes. 3 of our 5 Stoke-on-Trent bridges were for less than £50k, all on auction terraces in ST2 and ST4. Our current minimum is £30k.
Stoke-on-Trent · 5 auction deals · January 2024 to May 2026
3 of 5Stoke bridges under £50k
The largest was £80,000. Small loans carry the same legal work, so fees weigh more.
Current terms
Bridging now goes up to 80% LTV
From 13 October 2026, Lendlord bridging goes up to 80% LTV. A below-market buy can still reach 90% of the purchase price.
What the Stoke-on-Trent files show
Stoke-on-Trent has 5 deals, under the 10-deal bar for a median. The counts are this city's own files. Based on Lendlord aggregated data.
- 5
- Stoke-on-Trent deals among the 272 disclosed
- 5
- Auction purchases in this set
- 2
- Unmodernised or major works
- £10k to £80k
- Loan range, rounded to £5,000
Where the regional medians sit
Median loan, rate, LTV and days to funds for the West Midlands are on the West Midlands bridging loans page. This page keeps the Stoke-on-Trent deals, and does not repeat those medians.
Loan size on each Stoke-on-Trent file
The bars run from £10,000 to £80,000. The smallest was a top-up on a house we had already funded, below today's £30k minimum.
- ST2 2024
Loan amount: £10,000
- ST4 2024
Loan amount: £30,000
- ST2 2024 (2)
Loan amount: £80,000
- ST4 2025
Loan amount: £45,000
- ST4 2026
Loan amount: £65,000
Each loan we funded here
Sorted by year. Districts only, and every amount is rounded down to the nearest £5k.
| Loan | District and type | Funded | Condition | LTV | Rate pm | Days | Exit |
|---|---|---|---|---|---|---|---|
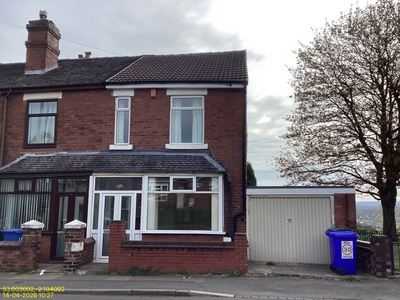
| £80,000 | ST2 end terrace | 2024 | Medium works | 75% | 1.00% | 25 | Refinance |
| £10,000 | ST2 end terrace | 2024 | Major works | 9% | 1.10% | 106 | Refinance |
| £30,000 | ST4 terrace | 2024 | Minor works | 54% | 1.10% | 45 | Refinance |
| £45,000 | ST4 terrace | 2025 | Medium works | 66% | 1.03% | 24 | Sale (live) |
| £65,000 | ST4 end terrace | 2026 | Unmodernised | 75% | 1.12% | 45 | Refinance (live) |
Every loan here funded an auction purchase. Unmodernised: no working kitchen or running water at purchase. Exits are repaid unless marked live. One row: further loan on a property already in this table. One row: below the current £30k product minimum. Aggregated from Lendlord's own data.
What a small bridge really costs
A £40k loan needs the same valuation, legal work and title checks as a £400k one. Those costs stay put while the loan shrinks, so the fee share rises.
Do the sum on total cost, not the rate. On a small loan, two months of interest can cost less than the valuation and legal fees. Ask for every fee in writing with the terms.
Stoke prices make this real. HM Land Registry shows a median terrace price of £120,000 in the city over September 2025 to August 2026.
Why fixed fees bite harder on a small Stoke loan
Legal and admin work costs the same whatever the loan size. Across the 5 Stoke files, all fees came to 5.4% to 18.7% of the amount borrowed.
| Fee | Local files | 272 disclosed bridging deals |
|---|---|---|
| Arrangement fee | 2% to 4% of the loan | Median 2% |
| Valuation fee | £495 (2 with no charge recorded) | Median £495 |
| Lender admin fee | £695 to £990 | Median £795 |
| Lender legal fees (estimated) | £750 to £1,995 | Median £1,550 |
| Exit fee | None on these files | 2 of 272 |
| All fees as a share of the loan | 5.4% to 18.7% | Fixed fees weigh most on small loans |
Arrangement fees ran from 2% to 4%. Two of the five files paid no valuation fee, and none paid an exit fee. Based on Lendlord aggregated data.
Builder and investor Sean Land, who bridges his projects with Lendlord, put the problem bluntly in a TikTok post:
Most lenders don’t want the small loan applications…
Regional mix
Purpose, condition and loan size for the region are charted once, on the regional bridging page.
Source: pooled Lendlord records.
Small-loan terms, headline vs actual
On a Stoke lot the minimum loan matters more than the floor rate.
| Headline term | Local files | 272 disclosed bridging deals |
|---|---|---|
| Loans from £30k | Smallest £10,000, largest £80,000 | £30k is the current product floor |
| From 0.75% pm | 0 of 5 at or below 0.75%. Lowest 1.00% (2024) | 5 of 272, none since 2025. Since 2025: lowest 0.92%, median 1.10% |
| Funding from 5 days | Today's process can fund within 5 days. AI checks your ID and bank statements in minutes, one solicitor acts for you and the lender, and loan papers are drafted automatically. On the files as funded, the fastest took 24 days. | Fastest 2 days. 2 of 218 timed deals within 7 days. Median 57 days |
| Up to 80% LTV | Highest gross LTV on these files 75% | The cap is now 80% of value. A below-market buy can still reach 90% of the purchase price. |
One older Stoke loan was a top-up below today's £30k minimum. New loans start at £30k. Aggregated from Lendlord's own data.
Every Stoke-on-Trent deal among the 272 disclosed
Based on Lendlord aggregated data.
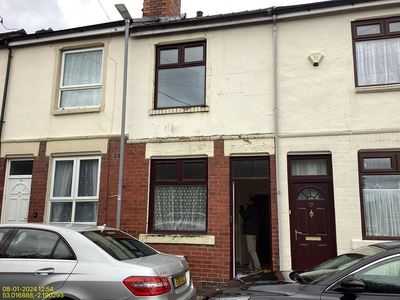
Auction · £30k bridge
ST4 terrace at the loan minimum
- £30,000
- Loan
- 54%
- LTV
- 1.10%
- Rate pm
- 45 days
- Completion
- Bought for £55,000. The bridge was £30,000 at 54% LTV, with £5,000 of light works.
- Interest was rolled up, and the refinance cleared it.
Funded 2024 · 12-month term · Refinance · Repaid
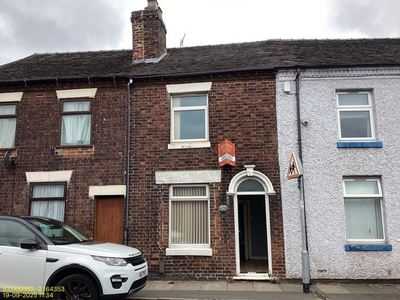
Auction · sale exit
ST4 terrace funded in 24 days
- £45,000
- Loan
- 66%
- LTV
- 1.03%
- Rate pm
- 24 days
- Completion
- The fastest Stoke file. Purchase £70,000, end value £110,000.
- The arrangement fee was 4%. Check the fee line as hard as the rate on a loan this size.
Funded 2025 · 12-month term · Sale · Live
Auction · six-month term
ST2 end terrace, the largest Stoke loan
- £80,000
- Loan
- 75%
- LTV
- 1.00%
- Rate pm
- 25 days
- Completion
- £80,000 at 1.00% a month, the lowest Stoke rate.
- A 6-month term for short works and a quick refinance.
Funded 2024 · 6-month term · Refinance · Repaid
Auction
ST2 end terrace
- £10,000
- Loan
- 9%
- LTV
- 1.10%
- Rate pm
- 106 days
- Completion
- Major works at purchase. Funded in 2024, 106 days. Exit Refinance.
Funded 2024 · 6-month term · Refinance · Repaid
Auction
ST4 end terrace
- £65,000
- Loan
- 75%
- LTV
- 1.12%
- Rate pm
- 45 days
- Completion
- Unmodernised, no kitchen or running water at purchase. Funded in 2026, 45 days. Exit Refinance.
Funded 2026 · 12-month term · Refinance · Live
Small Stoke lot and short on time? Speak to the team on 020 8191 9611.
Four steps between a Hanley sale room and funds
Our current process can fund from 5 days. The Stoke files funded in 24 to 106 days, and 4 of 5 landed within 45 days.
- Papers read by AI. ID, bank statements and company papers are checked in minutes, alongside identity, sanctions and fraud screening.
- Exit checked before terms. We stress-test the refinance or the resale at underwriting, not at the end of the term.
- One firm, both sides. Under dual representation a single solicitor acts for you and for us.
- Documents generated. Loan papers are produced once the offer conditions are met.
A loan near the £30k floor needs the same legal work as a large one. The steps do not get shorter, but you can start them before the sale.
Cost a sub-£50k bridge
The calculator opens on a bigger loan, so change it.
Indicative monthly rate
0.82%
Monthly interest
£2,050
Cost of the loan
- Total interest
- £24,600
- Arrangement fee (2%)
- £5,000
- Valuation fee
- £750
- Legal fee
- £1,500
- Admin fee
- £350
- Total cost of finance
- £32,200
Day one and exit
- Net advance on day one
- £245,000
- Gross loan repayable at exit
- £274,600
Low risk - best pricing
At or below 50% LTV you qualify for our lowest rate band and the fastest underwriting.
Month-by-month repayment schedule
| Month | Interest | Balance | Cost to redeem |
|---|---|---|---|
| 1 | £2,050 | £252,050 | £252,400 |
| 2 | £2,050 | £254,100 | £254,450 |
| 3 | £2,050 | £256,150 | £256,500 |
| 4 | £2,050 | £258,200 | £258,550 |
| 5 | £2,050 | £260,250 | £260,600 |
| 6 | £2,050 | £262,300 | £262,650 |
| 7 | £2,050 | £264,350 | £264,700 |
| 8 | £2,050 | £266,400 | £266,750 |
| 9 | £2,050 | £268,450 | £268,800 |
| 10 | £2,050 | £270,500 | £270,850 |
| 11 | £2,050 | £272,550 | £272,900 |
| 12 | £2,050 | £274,600 | £274,950 |
Indicative only, for deal screening - not an offer or a lending decision. Rates band by LTV, term and property type. Interest is charged on the loan amount at the headline monthly rate; the total is the same whichever structure you pick, only the cashflow differs. Third-party fees are estimates and vary by property and solicitor.
Who we can lend to on a low-value Potteries terrace
Cheap terraces qualify. The loan size and the ground under them are where we look first.
Stoke-on-Trent prices and rents
Land Registry recorded 2,261 standard sales in Stoke-on-Trent over September 2025 to August 2026. The median was £160,000. Terraces went for £120,000 and flats for £83,500.
In ST4 the median sale was £164,000, from 531 sales. ST2 came in at £165,000.
ONS data puts the average Stoke rent at £715 a month in August 2026. A year of that against the median price is about 5.4% gross, by our sum. Use it to screen, then value the actual house.
Figures from Land Registry price paid and ONS private rents.
What Stoke lets earn for Lendlord landlords
210 let homes in the city, as recorded by the Lendlord landlords who own them. The regional column gives the wider picture. Snapshot at 30 September 2026.
| Figure | Stoke-on-Trent |
|---|---|
| Median rent a month | £700 |
| Middle half of rents | £578 to £800 |
| Gross yield | 7.8% |
| Median value | £110,000 |
| Share with a mortgage | 49% |
| Homes counted | 210 let, 249 owned |
Rent is what owners record for each let. Value is their own estimate. The middle half covers the 25th to 75th percentile. Source: pooled Lendlord records.
A median Stoke let earns £700 a month on a £110,000 home.
A 75% buy-to-let loan on £110,000 is £82,500. That rent supports about £105,500 at 145% cover on a 5.5% stress rate, so value sets the remortgage. On a low-value lot, check the end valuation before you count on pulling cash out.
When a bridge earns its cost on a Stoke terrace
On a lot this cheap, the fees can outweigh the speed. Our five local files show both sides.
Where it paid off
- Quick auction completions. Case B funded in 24 days and Case C in 25.
- Large value gains after works. Case E bought at £110,000 and was valued at £190,000 after a £40,000 refurb.
- A workable remortgage. On a typical £70,000 bridge here, our rent test clears the bar.
Where it strained
- Fees as a share of the loan. On these files they reached 18.7% of the amount borrowed.
- Tiny top-ups. The £10,000 further advance sits below today's £30k minimum.
- Slow heavy works. The one major-works file took 106 days to fund.
Energy ratings across the city
From October 2016 to October 2026, 62,680 domestic EPCs were lodged in Stoke-on-Trent. Fewer than half, 48.6%, reached C or better.
- Band A
Share of certificates: 0.5% (289)
- Band B
Share of certificates: 9.0% (5,657)
- Band C
Share of certificates: 39.1% (24,507)
- Band D
Share of certificates: 38.6% (24,195)
- Band E
Share of certificates: 11.0% (6,867)
- Band F
Share of certificates: 1.3% (821)
- Band G
Share of certificates: 0.5% (344)
Auction rooms selling Stoke lots
Butters John Bee sells from Festival Park. Bond Wolfe carries the odd Stoke lot in Birmingham.
Butters John Bee
DoubleTree, Festival Park, Hanley. Next sales: 26 October 2026 and 7 December 2026.
Bond Wolfe
Birmingham, occasional Stoke lots. Next sales: 22 October 2026.
Checked 7 October 2026. We do not work for either house.
Where in the Potteries we have lent
Our Stoke files cluster in a few ST districts, all low-value terraces.
- ST4: 3 deals
- ST2: 2 deals
Local rent and value figures come from homes recorded in Stoke-on-Trent.
Nearby West Midlands pages with their own deals:
Small-loan bridge types we funded in Stoke
Counts are our own Stoke files; each links the guide for that use.
- Auction bridging (5 files)
- Unmortgageable property (1 file)
Before you bid on a Potteries lot
Ground first, then the council.
What to send with a Stoke-on-Trent application
Pick the items that match your exit. A sale and a remortgage need different evidence.
Exiting a small Stoke bridge
Small mortgages are harder to place. Some lenders set a minimum loan or a minimum property value.
- Check the mortgage floor. Ask your broker which lenders accept a property value at your level.
- Keep works light. On a low-value terrace, a big refurb can cost more than it adds.
- Choose sale if refinance will not fit. 1 of the 5 Stoke bridges exit by sale.
- Repay early if you can. Interest stops when the loan is repaid.
Guides that fit a small-loan auction bridge
Every Stoke file we funded was an auction terrace, and 3 of 5 borrowed under £50k. Start with the cost guide, then the refurbishment pages.
- The full cost of a bridge, worked through: Fees, interest and term on one page.
- Bridging for a refurbishment project: For lots like Case E and its £40,000 works.
- A refurb case study with costs and exit: One project from purchase to repayment.
- Model the lot in the deal analyser: Price, works and rent in one place.
- How long bridging takes across our deals: Timings from application to funds.
- Derby bridging files nearby: A Midlands city page with its own deals.
Customer reviews on Trustpilot
Lendlord customers on finance and the platform, word for word from Trustpilot.
I've used these guys quite a few times…
“I've used these guys quite a few times now there always quick and easy to work with 100% recommend”
Aaron H
Verified review on Trustpilot from Aaron HI have used Lendlord for a remortgage…
“I have used Lendlord for a remortgage and a property purchase. They are professional, friendly and knowledgable. Simmy in particular has been consistently brilliant.”
Oliver
Verified review on Trustpilot from OliverThis Software is amazing and has really…
“This Software is amazing and has really helped me manage my portfolio. The bank integration and reconciliation is super easy.”
Sarah
Verified review on Trustpilot from Sarah
Questions on small Stoke bridges
Will anyone lend on a cheap Stoke terrace?
We did, 5 times among the 272 disclosed deals, from £10,000 to £80,000. New loans start at £30k.
What is the smallest bridging loan you do?
£30k today. One older Stoke file was a smaller top-up on a house we had already funded.
Is old coal mining a problem for a bridge here?
Not if it is checked. We want a CON29M or the GOV.UK coal mining check on file before completion.
How quickly did your Stoke bridges fund?
Between 24 and 106 days from application to funds. Five deals is too few for a fair median.
Clare Harris
Bridging Loan Specialist and Director of Growth at Lendlord · 12+ years in loans and lending · Checked each Stoke loan size and fee against the file
Last reviewed
Method for these figures
There are 5 Stoke deals in the 272 recent Lendlord bridging deals approved for disclosure, funded January 2024 to May 2026.
The table and cases are Stoke deals. Loans are rounded down to the nearest £5k and shown by district, never by street.
Small Stoke lot, tight margin?
Send us the lot. We will show the full cost, fees included, before you commit.
Who provides the service
Lendlord Limited, company 11973095, runs the landlord software. The registered office is Churchill House, 137-139 Brent Street, London, NW4 4DJ. The public name is Lendlord.
Lendlord Finance Limited, company 13696524, uses the trading name Lendlord Capital for bridging. It lends that loan itself. Mortgage and remortgage applications are a separate service.
Lendlord Finance Limited arranges those mortgages as an appointed representative of Windfall Limited. The FCA authorises Windfall Limited under firm reference 225908. The mortgage itself comes from a lender on that panel.
Lendlord Limited is registered for account information services, so a bank feed can be read with your consent. That registration is not permission to lend, and it is not permission to arrange a mortgage.
Bridging on this page is secured on property in England and Wales. Lending here goes up to 80% LTV. A below-market buy can still reach 90% of the purchase price.