Derby Bridging Loans, File by File
4 Derby bridges, three of them in DE22. A typical Derby purchase bridged for a year needs about £870 a month to refinance; recorded lets bring in £850.
Derby · 4 deals · October 2023 to May 2025
£870Rent a typical Derby bridge needs
Recorded Derby lets: £850 a month. Close, so check the actual street.
Current terms
Bridging now goes up to 80% LTV
From 13 October 2026, Lendlord bridging goes up to 80% LTV. A below-market buy can still reach 90% of the purchase price.
All four Derby bridges
The four Derby files, with amounts rounded down to £5k and only the postcode district shown.
| Loan | District and type | Funded | Condition | LTV | Rate pm | Days | Exit |
|---|---|---|---|---|---|---|---|
| £125,000 | DE73 detached | 2023 | Minor works | 72% | 1.04% | 32 | Sale |
| £75,000 | DE22 end terrace | 2024 | Medium works | 69% | 0.95% | Not timed | Refinance |
| £55,000 | DE22 terrace | 2024 | Unmodernised | 60% | 1.15% | 44 | Refinance |
| £105,000 | DE22 terrace | 2025 | Not recorded | 75% | 1.10% | 40 | Sale |
All four Derby loans are repaid, so no row is marked live. Amounts are rounded down to £5k and the funded year stands in for the date. Unmodernised: no working kitchen or running water at purchase. Exits are repaid unless marked live. One row: timeline outlier, excluded from speed figures. One row: further loan on a property already in this table. Based on Lendlord aggregated data.
What the Derby files show
Derby has 4 deals, under the 10-deal bar for a median. The counts are this city's own files. Source: pooled Lendlord records.
- 4
- Derby deals among the 272 disclosed
- 2
- Auction purchases in this set
- 1
- Unmodernised or major works
- £55k to £125k
- Loan range, rounded to £5,000
Where the regional medians sit
Median loan, rate, LTV and days to funds for the East Midlands are on the East Midlands bridging loans page. This page keeps the Derby deals, and does not repeat those medians.
Days from application to funds in Derby
Three of the four Derby loans were timed. All three funded in 32 to 44 days, against a median of 57 days across the 272 disclosed deals.
- DE73 2023
Days to funds: 32 days
- DE22 2024
Days to funds: 44 days
- DE22 2025
Days to funds: 40 days
Three Derby files
Based on Lendlord aggregated data.
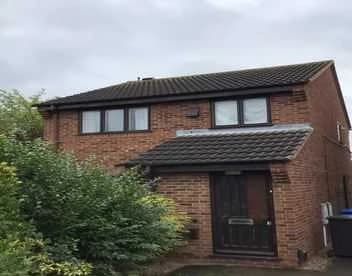
Auction · sold
DE73 home, the largest Derby loan
- £125,000
- Loan
- 72%
- LTV
- 1.04%
- Rate pm
- 32 days
- Completion
- £125,000 on a £170,000 purchase, funded in 32 days.
- Valued at £250,000 after £30,000 of works and sold.
Funded 2023 · 12-month term · Sale · Repaid
Buy-to-let · lowest rate
DE22 home at 0.95% a month
- £75,000
- Loan
- 69%
- LTV
- 0.95%
- Rate pm
- Not timed
- Completion
- Bought for £110,000 with £20,000 of works.
- Refinanced against a £200,000 valuation.
Funded 2024 · 12-month term · Refinance · Repaid
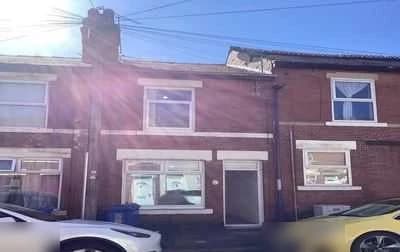
Capital raise · 9 months
DE22 terrace, cash raised on equity
- £105,000
- Loan
- 75%
- LTV
- 1.10%
- Rate pm
- 40 days
- Completion
- £105,000 at 75% LTV, interest serviced monthly.
- Funded in 40 days and repaid by sale.
Funded 2025 · 9-month term · Sale · Repaid
A Derby bridge against Derby rents
The median purchase price in Derby deal analyses on Lendlord is £167,500. Bridged at 69% for a year at 1.09% a month, roughly £130,500 is owed when you refinance.
Recorded Derby lets bring in a median £850 a month. A lender testing at 145% cover on 5.5% would lend about £128,000 on that, which falls short of the balance by a small margin. The house needs around £870 a month.
On value, you need about £174,500 after works for a 75% mortgage to repay the bridge.
Source: pooled Lendlord records.
Planning a small HMO in the city centre? Check the Article 4 rule with us on 020 8191 9611.
Derby rules inside the inner ring road
One planning rule changed in 2025. It matters most for inner-city terraces.
What landlords model in Derby
38 Derby analyses saved on Lendlord in 12 months: median price £167,500, expected rent £1,000 a month, 71% set up as buy-to-let.
Aggregated from Lendlord's own data.
Recorded rents on Derby lets
135 let homes. Snapshot at 30 September 2026.
| Figure | Derby |
|---|---|
| Median rent a month | £850 |
| Middle half of rents | £784 to £975 |
| Gross yield | 6.5% |
| Median value | £161,750 |
| Share with a mortgage | 67% |
| Homes counted | 135 let, 154 owned |
Rents are as owners record them; values are their own estimates. Based on Lendlord aggregated data.
Derby mortgages
107 live mortgages recorded on Derby homes, at a median 4.74%. 22% of dated mortgages expire within 12 months.
Source: pooled Lendlord records.
Derby prices and rents
2,559 standard sales over September 2025 to August 2026, at a median £215,000. Terraces £165,000, semis £218,000.
Three of our files sit in DE22, where 537 sales had a median of £250,000.
ONS puts the average Derby rent at £860 in August 2026, up 3.1% on a year earlier.
See Land Registry price paid for the sales and ONS private rents for the rent series.
Cost a Derby bridge
Use the bridging loan calculator: start at £115,500 and 1.09% a month over 12 months.
Indicative monthly rate
0.82%
Monthly interest
£2,050
Cost of the loan
- Total interest
- £24,600
- Arrangement fee (2%)
- £5,000
- Valuation fee
- £750
- Legal fee
- £1,500
- Admin fee
- £350
- Total cost of finance
- £32,200
Day one and exit
- Net advance on day one
- £245,000
- Gross loan repayable at exit
- £274,600
Low risk - best pricing
At or below 50% LTV you qualify for our lowest rate band and the fastest underwriting.
Month-by-month repayment schedule
| Month | Interest | Balance | Cost to redeem |
|---|---|---|---|
| 1 | £2,050 | £252,050 | £252,400 |
| 2 | £2,050 | £254,100 | £254,450 |
| 3 | £2,050 | £256,150 | £256,500 |
| 4 | £2,050 | £258,200 | £258,550 |
| 5 | £2,050 | £260,250 | £260,600 |
| 6 | £2,050 | £262,300 | £262,650 |
| 7 | £2,050 | £264,350 | £264,700 |
| 8 | £2,050 | £266,400 | £266,750 |
| 9 | £2,050 | £268,450 | £268,800 |
| 10 | £2,050 | £270,500 | £270,850 |
| 11 | £2,050 | £272,550 | £272,900 |
| 12 | £2,050 | £274,600 | £274,950 |
Indicative only, for deal screening - not an offer or a lending decision. Rates band by LTV, term and property type. Interest is charged on the loan amount at the headline monthly rate; the total is the same whichever structure you pick, only the cashflow differs. Third-party fees are estimates and vary by property and solicitor.
Headline terms against Derby files
How four real Derby files compare with the advertised terms.
| Headline term | Local files | 272 disclosed bridging deals |
|---|---|---|
| Loans from £30k | Smallest £55,000, largest £125,000 | £30k is the current product floor |
| From 0.75% pm | 0 of 4 at or below 0.75%. Lowest 0.95% (2024) | 5 of 272, none since 2025. Since 2025: lowest 0.92%, median 1.10% |
| Funding from 5 days | Today's process can fund within 5 days. AI checks your ID and bank statements in minutes, one solicitor acts for you and the lender, and loan papers are drafted automatically. On the files as funded, the fastest took 32 days. | Fastest 2 days. 2 of 218 timed deals within 7 days. Median 57 days |
| Up to 80% LTV | Highest gross LTV on these files 75% | The cap is now 80% of value. A below-market buy can still reach 90% of the purchase price. |
The 75% ceiling applied to all four Derby files. Aggregated from Lendlord's own data.
Derby bridging fees, line by line
Arrangement, valuation, admin and legal fees on our Derby loans, next to the median across the book. Add them to the interest before you compare quotes.
| Fee | Local files | 272 disclosed bridging deals |
|---|---|---|
| Arrangement fee | 2% of the loan | Median 2% |
| Valuation fee | £450 to £495 (1 with no charge recorded) | Median £495 |
| Lender admin fee | £495 to £795 | Median £795 |
| Lender legal fees (estimated) | £1,300 to £1,550 | Median £1,550 |
| Exit fee | None on these files | 2 of 272 |
| All fees as a share of the loan | 4% to 5.4% | Fixed fees weigh most on small loans |
Legal fees are the lender's estimate at offer. No charge recorded usually means a desktop valuation. Based on Lendlord aggregated data.
Derby bridging eligibility: what the files had in common
A pre-check before you apply. Final terms depend on the valuation and your exit.
Applying for a Derby bridge, step by step
Four steps from application to funds. Steps run side by side, which is how the process can fund from 5 days.
- Upload your documents. AI reads your ID, bank statements and company papers, and runs identity and fraud checks in minutes.
- Get indicative terms. Underwriting tests your refinance or sale exit against rate and price moves.
- One solicitor for both sides. Legal questions stay with one firm instead of passing between two.
- Sign the generated loan papers. Funds release once the offer conditions are met.
On a Derby auction lot, send the legal pack with the application so the solicitor starts on day one.
Property investor Corey Rees, who arranges his bridges through Lendlord's finance hub, explained why timing matters in an Instagram post:
…property deals fall out of bed because investors can’t get the finance quick enough. That’s why I use the Lendlord finance hub to get my bridges done quickly because in this game speed is key…
What to send with a Derby application
Our loans in the city split between auction buys, a buy-to-let refinance and a capital raise. Each route needs different papers, so match the list to yours.
Auction buyers and refinancers on Trustpilot
Three Lendlord customers on deadlines, rates and getting a bridge through, as posted on Trustpilot.
Excellent loan service
“I have used Lendlord for bridge finance for the properties purchased at auction on several occasions. We have variable deadlines between one week to 4 weeks and on every occasion, they have met with the deadline successfully…”
Himanshu Sharma
Verified review on Trustpilot from Himanshu SharmaGreat work
“I had my bridge, finance and remortgage through lendlord I will definitely be using them again. They were very helpful & Very efficient”
Gordon
Verified review on Trustpilot from GordonAccessible and prompt response…
“Accessible people and prompt response times from start to finish with all matter of queries. Also, reviewed our interest rate part way through and were able to get a revised mortgage offer towards the end of the process with a lower mortgage interest rate.”
Patrick Shannon
Verified review on Trustpilot from Patrick Shannon
Auctions with Derby lots
Bagshaws is based on the Cornmarket. SDL Property Auctions sells from Chilwell with livestream and online sales.
Bagshaws Residential Property Auctions
The Cornmarket, Derby. Next sales: 17 November 2026 and 15 December 2026.
SDL Property Auctions
Chilwell, Nottingham. Next sales: 22 October 2026 and 28 October 2026.
Taken from each auction calendar at the last check. Lendlord is independent of both.
Derby districts we have bridged in
Three of our four are in DE22; one is in DE73.
- DE22: 3 deals
- DE73: 1 deal
Platform rent and value figures come from let homes in Derby.
Nearby city pages built on our own deals:
How our Derby bridges were used
A link to the guide for every route these four took.
- Auction bridging (2 files)
- Bridging for a rental purchase (1 file)
- Unmortgageable property (1 file)
Further reading for Derby auction and refinance buyers
Two of these loans bought at auction and two exited by refinance. The guides below cover the steps behind both, and the costs worth checking.
- How auction buyers funded their lots: Auction-tagged files among the 272 disclosed deals.
- Bridging for an auction purchase: For lots like the DE73 and DE22 buys.
- Passing the buy-to-let stress test: Useful where rent sits close to the refinance line.
- Bridge to let, then remortgage: The route the DE22 end terrace took.
- Current monthly bridging rates: Local files ranged from 0.95% to 1.15% a month.
- Company structures for bridging: Why borrowers here used a limited company.
Energy ratings in Derby
Derby lodged 62,767 domestic certificates in the decade to the latest update; 48.5% were C or better.
- Band A
Share of certificates: 0.7% (458)
- Band B
Share of certificates: 11.2% (7,002)
- Band C
Share of certificates: 36.6% (22,956)
- Band D
Share of certificates: 37.8% (23,721)
- Band E
Share of certificates: 11.7% (7,343)
- Band F
Share of certificates: 1.6% (1,003)
- Band G
Share of certificates: 0.5% (284)
Exiting a Derby bridge
The rent test is close in Derby, so a small change in rent or deposit moves it.
- Check the street rent. Use recorded lets on the street, not the town median.
- Plan the deposit. A slightly lower remortgage loan passes the rent test.
- Mind the inner ring road. An HMO plan inside it needs planning permission first.
- Keep sale open. 2 of the 4 Derby files sold.
Four Derby loans, four things to keep
- All 4 repaid. Loans ran from £55,000 to £125,000, and none is still live.
- Quick when timed. The three timed files funded in 32 to 44 days.
- The rent test is close. Refinancing a typical £167,500 buy needs about £870 a month, a little above the £850 on recorded lets.
- Planning comes first for HMOs. Since 3 May 2025, a small HMO conversion inside the inner ring road needs permission.
Derby bridging FAQs
Who funds bridges in Derby?
Lendlord funded 4 Derby bridges among the 272 disclosed deals, all repaid, with loans from £55,000 to £125,000.
Can I convert a Derby house to an HMO with a bridge?
Inside the inner ring road and in Arboretum ward you need planning permission first, since 3 May 2025. Outside it, small HMOs can still use permitted development.
How fast did your Derby bridges fund?
Between 32 and 44 days. Four deals is too few for a median.
Does Derby need a coal search?
Derby has no coal resources, but run the GOV.UK coal mining check by postcode to be sure.
Clare Harris
Bridging Loan Specialist and Director of Growth at Lendlord · 12+ years in loans and lending · Checked each Derby file and the inner ring road rule
Last reviewed
About these figures
Derby has 4 deals in the 272 recent Lendlord bridging deals approved for disclosure, funded October 2023 to May 2025, so every file is shown and no median is published.
Platform figures for Derby (rents, mortgages, deal analyses) need 10 records before we print them.
Derby deal on the table?
Send the address and the plan. We will check the rent test and the planning rule with you.
Who provides the service
Lendlord Limited, company 11973095, runs the landlord software. The registered office is Churchill House, 137-139 Brent Street, London, NW4 4DJ. The public name is Lendlord.
Lendlord Finance Limited, company 13696524, uses the trading name Lendlord Capital for bridging. It lends that loan itself. Mortgage and remortgage applications are a separate service.
Lendlord Finance Limited arranges those mortgages as an appointed representative of Windfall Limited. The FCA authorises Windfall Limited under firm reference 225908. The mortgage itself comes from a lender on that panel.
Lendlord Limited is registered for account information services, so a bank feed can be read with your consent. That registration is not permission to lend, and it is not permission to arrange a mortgage.
Bridging on this page is secured on property in England and Wales. Lending here goes up to 80% LTV. A below-market buy can still reach 90% of the purchase price.