Bridging Loans in Plymouth: What 12 Real Deals Show
10 of our 12 Plymouth bridges paid for auction lots, nearly all terraces in PL1 to PL5. Median loan £110,000, and a median 52 days from application to funds. Today our process can fund from 5 days.
10 of 12Plymouth bridges were auction buys
11 of the 12 were repaid by a buy-to-let remortgage. Only 1 was sold.
Current terms
Bridging now goes up to 80% LTV
From 13 October 2026, Lendlord bridging goes up to 80% LTV. A below-market buy can still reach 90% of the purchase price.
Four Plymouth lots, photo and figures
Anonymised auction files from the 272 recent Lendlord bridging deals approved for disclosure (November 2023 to January 2026). Photos come from each file's valuation pack; figures are as funded. *Completion counts from the day you applied to the day funds were released. Today's process can fund a bridge like these in 5 days. Based on Lendlord aggregated data.
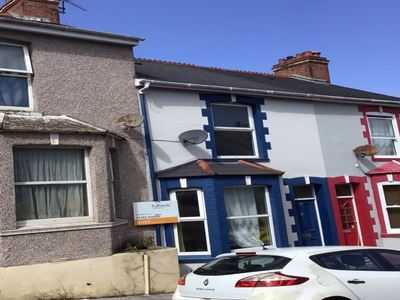
Auction · no kitchen or water
PL2 terrace funded unmodernised
- £105,000
- Loan
- 75%
- LTV
- 1.12%
- Rate pm
- 67 days
- Completion*
- Purchase £140,000, works £5,000, end value £185,000. Interest was serviced monthly.
- A six-month term still needed an extension before the remortgage cleared the bridge.
Funded 2025 · 6-month term · Refinance · Repaid
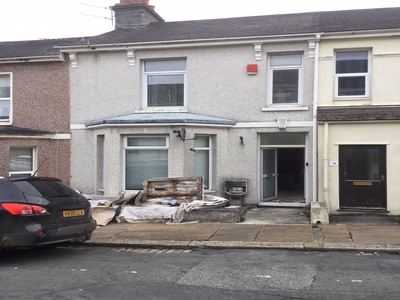
Auction · light works · extended
PL4 four-bed terrace after a hammer price
- £85,000
- Loan
- 75%
- LTV
- 0.99%
- Rate pm
- 38 days
- Completion*
- Purchase £115,000, works £10,000, end value £170,000 (48% uplift).
- Funds in 38 days. The refinance ran past the 12-month term, so budget a spare month of interest.
Funded 2023 · 12-month term · Refinance · Repaid
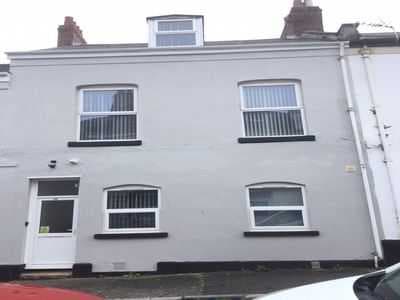
Auction · HMO conversion
PL2 terrace bought for multi-let works
- £110,000
- Loan
- 75%
- LTV
- 0.99%
- Rate pm
- 38 days
- Completion*
- Purchase £150,000, works £10,000, end value £250,000. That is a 67% uplift once the rooms are let.
- Interest was serviced monthly. Check Article 4 and licensing before you bid on this stock.
Funded 2023 · 12-month term · Refinance · Repaid
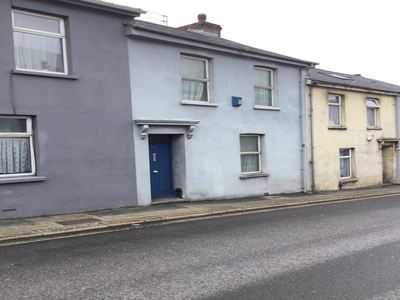
Auction · slow file · flats plan
PL3 terrace with a long underwrite
- £80,000
- Loan
- 66%
- LTV
- 1.03%
- Rate pm
- 267 days
- Completion*
- Purchase £125,000, works £20,000, end value £190,000. Interest was rolled up.
- Application to funds took 267 days. Never plan a 28-day auction clock on the slowest file.
Funded 2024 · 12-month term · Refinance · Repaid
These four lots took 38 to 267 days to fund. On our current process, a bridge like them can complete in 5 days. See what changed.
Plymouth bridging in four numbers
Every local file in the 272 disclosed deals, funded November 2023 to January 2026. Source: pooled Lendlord records.
- £110,000
- Median Plymouth loan
- 1.04%
- Median rate per month
- 52 days
- Median days to funds, as funded
- 92%
- Repaid by refinance
Where the regional medians sit
Median loan, rate, LTV and days to funds for the South West are on the South West bridging loans page. This page keeps the Plymouth deals, and does not repeat those medians.
A terrace, a hammer price and a remortgage
The Plymouth pattern is tight. Buy a terrace at auction, spend around £10,000 on works, then refinance onto a buy-to-let mortgage.
That shapes the exit. A mortgage lender will not lend on a house without a working kitchen. The bridge buys you the works window, and the remortgage pays it off. Plan the second loan before you bid on the first.
PL4 is where we lend most, with 5 of the 12 deals. Mutley, Greenbank and Lipson stock dominates there, and several of those wards sit inside the city's HMO Article 4 area.
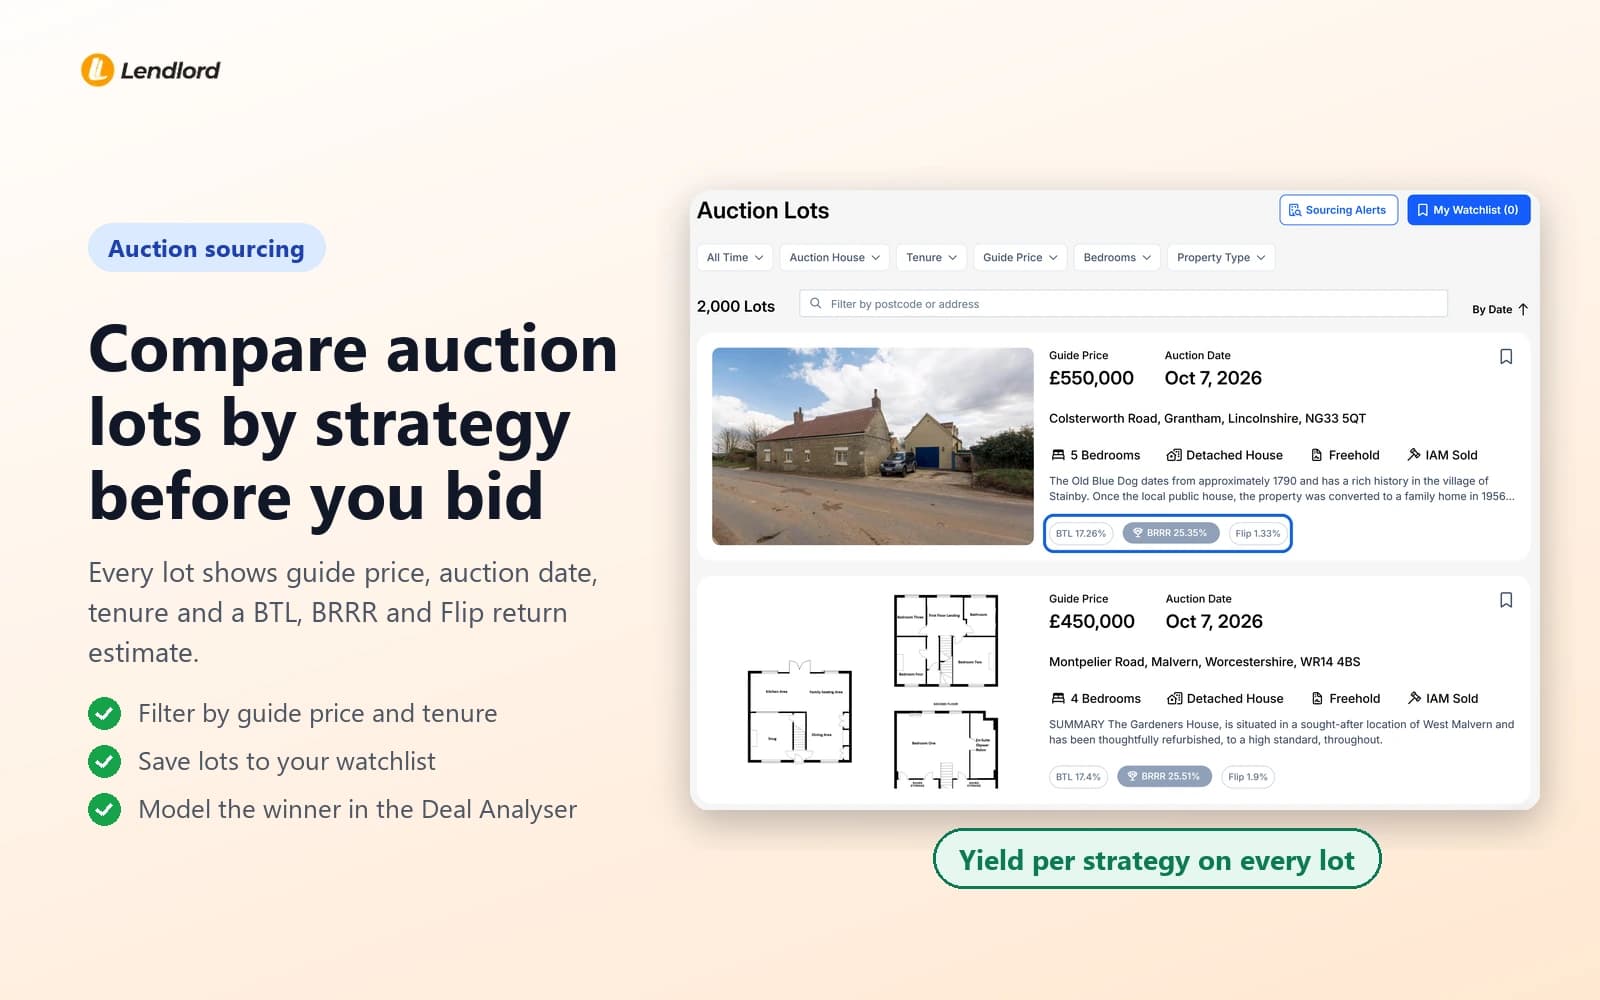
What the Plymouth bridges paid for
Purpose of each loan, one slice per file.
- Auction
- 83.3%
- Refurbishment
- 8.3%
- Buy-to-let
- 8.3%
One refurbishment loan and one buy-to-let purchase make up the rest.
Every Plymouth bridge, row by row
Postcode district and funded year only. Loans rounded down to the nearest £5k.
| District and type | Funded | Purpose and condition | Loan | LTV | Rate pm | Days | Exit |
|---|---|---|---|---|---|---|---|
| PL2 terrace | 2023 | Auction, major works | £110,000 | 75% | 0.99% | 38 | Refinance |
| PL4 terrace | 2023 | Auction, minor works | £85,000 | 75% | 0.99% | 38 | Refinance |
| PL1 terrace | 2024 | Auction, unmodernised | £110,000 | 62% | 1.04% | 104 | Refinance |
| PL3 terrace | 2024 | Auction, medium works | £80,000 | 66% | 1.03% | 267 | Refinance |
| PL4 terrace | 2024 | Auction, minor works | £355,000 | 75% | 1.06% | 87 | Sale |
| PL4 terrace | 2024 | Auction, minor works | £155,000 | 75% | 1.05% | 34 | Refinance |
| PL5 semi | 2024 | Auction, minor works | £60,000 | 65% | 1.02% | 257 | Refinance |
| PL1 terrace | 2025 | BTL, unmodernised | £130,000 | 75% | 1.12% | 93 | Refinance |
| PL2 terrace | 2025 | Auction, unmodernised | £105,000 | 75% | 1.12% | 67 | Refinance |
| PL3 terrace | 2025 | Auction, unmodernised | £90,000 | 75% | 1.05% | 14 | Refinance (live) |
| PL4 terrace | 2025 | Refurb, minor works | £110,000 | 67% | 1.04% | 25 | Refinance |
| PL4 terrace | 2026 | Auction, unmodernised | £95,000 | 75% | 1.05% | 33 | Refinance (live) |
Days to funds counts from application to the day the money was released. The steps that now shorten each stage are under 5-day funding, below the terms table. Unmodernised: no working kitchen or running water at purchase. Exits are repaid unless marked live. Based on Lendlord aggregated data.
Can you bridge a no-kitchen terrace in Plymouth?
Yes. 5 of our 12 Plymouth bridges bought a terrace in that state, with no running water either. Here they are against the rest of the local files.
| Figure | No kitchen or water (5) | Other files (7) |
|---|---|---|
| Districts | PL1, PL2, PL3, PL4 | PL2, PL3, PL4, PL5 |
| Median loan | £105,000 | £110,000 |
| Funded at 75% LTV | 4 of 5 | 4 of 7 |
| Days to funds | 14 to 104 (median 67) | 25 to 267 (median 38) |
| Exit | 5 refinance (2 still live) | 6 refinance, 1 sale |
Condition is the tag on each file at funding. Loans rounded down to the nearest £5k. Days are counted on the files as funded. Source: pooled Lendlord records.
These files took longer on average, but none ran past 104 days. The two files that took over 250 days were tidier houses. On these lots the remortgage sets the exit, so line it up ahead of the auction.
4 of 5 borrowed at the 75% cap in place when they funded. The cap is now 80% LTV. Borrowing at the top still leaves no room in the loan for overruns, so hold the works contingency in cash. For lender rules on these homes, see how lenders treat an unmodernised house.
What a Plymouth terrace needs for us to lend
Our 12 local files follow one pattern: an auction terrace, a works plan and a remortgage at the end. These are the points we check.
Headline terms against Plymouth's real files
Our product pages quote a floor rate and our fastest funding time. Here is how our files compare.
| Headline term | Local files | 272 disclosed bridging deals |
|---|---|---|
| From 0.75% pm | 0 of 12 at or below 0.75%. Lowest 0.99% (2023) | 5 of 272, none since 2025. Since 2025: lowest 0.92%, median 1.10% |
| Funding from 5 days | Today's process can fund within 5 days. AI checks your ID and bank statements in minutes, one solicitor acts for you and the lender, and loan papers are drafted automatically. On the files as funded, the fastest took 14 days. | Fastest 2 days. 2 of 218 timed deals within 7 days. Median 57 days |
| Up to 80% LTV | Highest gross LTV on these files 75% | The cap is now 80% of value. A below-market buy can still reach 90% of the purchase price. |
| Loans from £30k | Smallest £60,000, largest £355,000 | £30k is the current product floor |
Rates are monthly and move with LTV, condition and exit. Indicative terms follow once we see the lot. Aggregated from Lendlord's own data.
How we fund from 5 days
Our process is built to fund a bridge from 5 days. Steps that used to queue behind each other now run side by side.
- Documents in minutes. AI reads your ID, bank statements, company papers and exit evidence, and runs identity, sanctions and fraud checks at the same time.
- Terms the same day. Underwriting is AI-assisted, and your refinance or sale exit is stress-tested against rate and price moves before the offer.
- One solicitor for both sides. Dual representation means legal questions stop bouncing between your firm and the lender's.
- Loan papers drafted for you. The facility documents are generated once the offer conditions are met.
The valuation visit and the auction legal pack still set the pace on these terraces. Send the legal pack and proof of deposit with your application, not after the hammer falls.
Plymouth, in one minute
The bid, the loan and the exit on a local terrace.
Line up the exit first. Almost every local file was repaid by remortgage.
Three things our Plymouth files show that a rate table cannot
Small groups are shown as counts, not averages.
Plymouth refinances, the region sells
92% of our bridges in the city were repaid by a remortgage. Line up the mortgage first.
PL4 files cleared quickest
4 of our 5 PL4 files funded within 40 days, and the slowest took 87. On our own files, a PL4 lot is the likeliest to complete inside an auction window.
Little cash left in after refinance
On our own sum, a 75% remortgage on the end value clears all 4 case bridges. 2 would hand back every pound put in, and the most left in is £6,250. That is before interest, fees and stamp duty.
Source: those 272 deals. Plymouth November 2023 to January 2026, the region October 2023 to July 2026. Case sums use figures rounded to the nearest £5k. Based on Lendlord aggregated data.
Price a Plymouth bridge
Start from the Plymouth median: £110,000 at 1.04% a month over 12 months, with a 2% arrangement fee. Then change the figures to your lot.
Indicative monthly rate
0.82%
Monthly interest
£2,050
Cost of the loan
- Total interest
- £24,600
- Arrangement fee (2%)
- £5,000
- Valuation fee
- £750
- Legal fee
- £1,500
- Admin fee
- £350
- Total cost of finance
- £32,200
Day one and exit
- Net advance on day one
- £245,000
- Gross loan repayable at exit
- £274,600
Low risk - best pricing
At or below 50% LTV you qualify for our lowest rate band and the fastest underwriting.
Month-by-month repayment schedule
| Month | Interest | Balance | Cost to redeem |
|---|---|---|---|
| 1 | £2,050 | £252,050 | £252,400 |
| 2 | £2,050 | £254,100 | £254,450 |
| 3 | £2,050 | £256,150 | £256,500 |
| 4 | £2,050 | £258,200 | £258,550 |
| 5 | £2,050 | £260,250 | £260,600 |
| 6 | £2,050 | £262,300 | £262,650 |
| 7 | £2,050 | £264,350 | £264,700 |
| 8 | £2,050 | £266,400 | £266,750 |
| 9 | £2,050 | £268,450 | £268,800 |
| 10 | £2,050 | £270,500 | £270,850 |
| 11 | £2,050 | £272,550 | £272,900 |
| 12 | £2,050 | £274,600 | £274,950 |
Indicative only, for deal screening - not an offer or a lending decision. Rates band by LTV, term and property type. Interest is charged on the loan amount at the headline monthly rate; the total is the same whichever structure you pick, only the cashflow differs. Third-party fees are estimates and vary by property and solicitor.
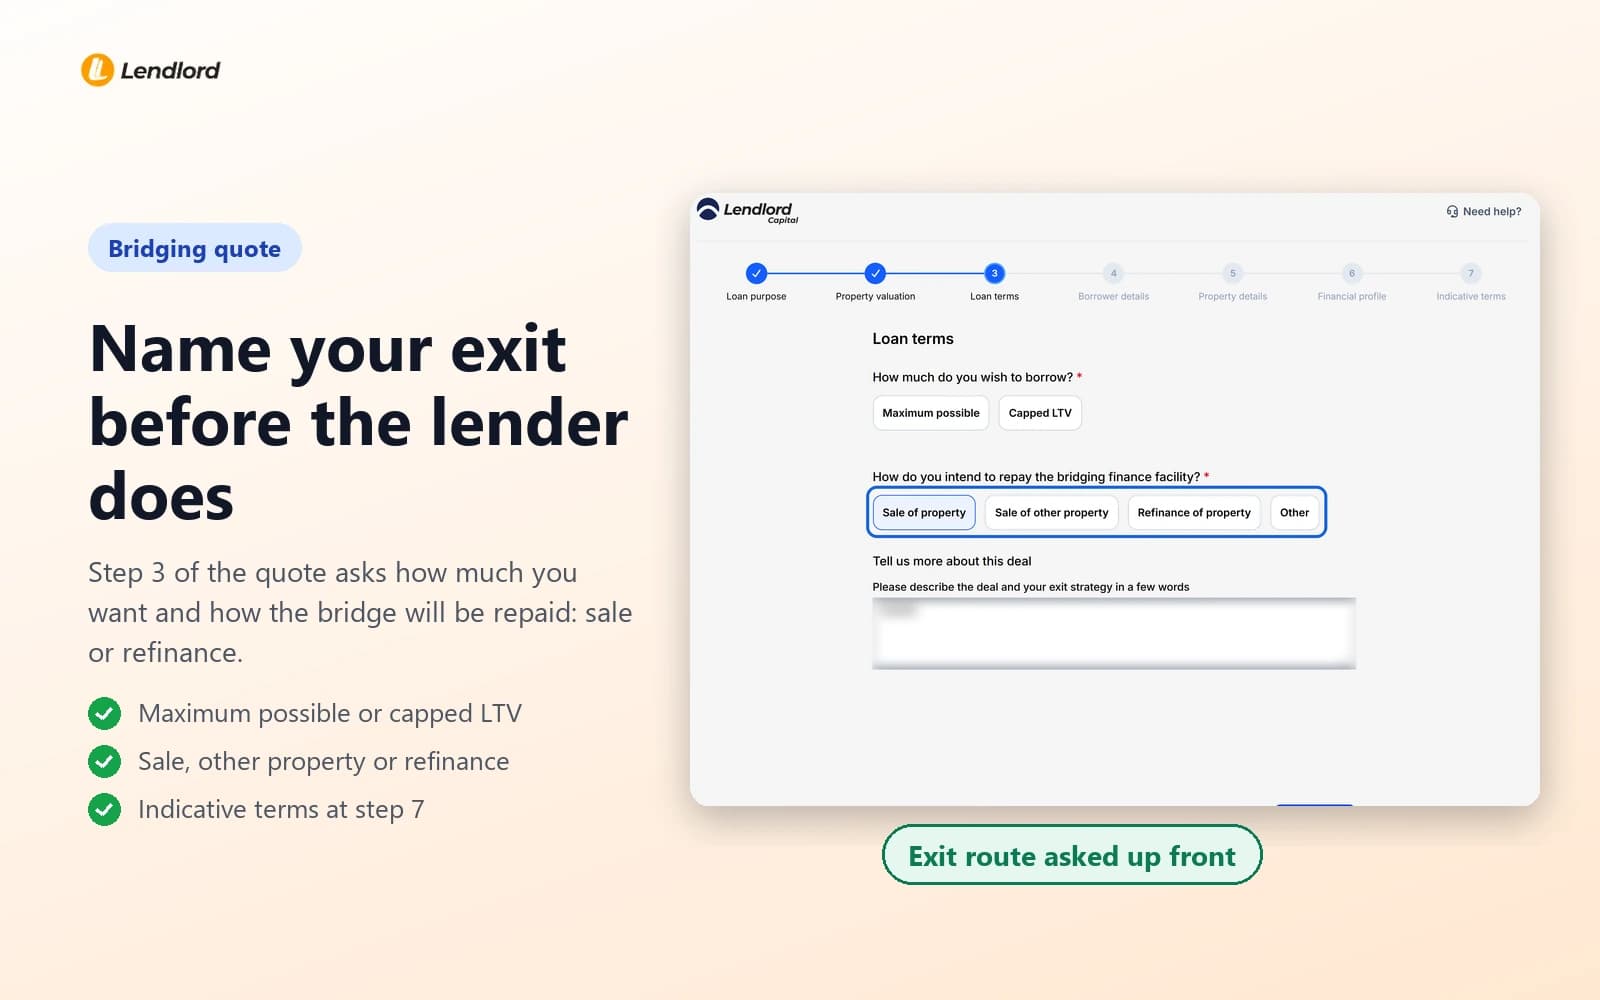
Filling in the application, step by step
Thirty seconds, using the median local figures from the table above.
Purpose, property, loan size and exit, step by step
What a Plymouth bridge costs beyond the monthly rate
The rate is one line on the offer. Here is every other fee our loans in the city carried, set against the wider deal set.
| Fee | Local files | 272 disclosed bridging deals |
|---|---|---|
| Arrangement fee | 1.7% to 2% of the loan | Median 2% |
| Valuation fee | £247 to £1,800 (3 with no charge recorded) | Median £495 |
| Lender admin fee | £695 to £990 | Median £795 |
| Lender legal fees (estimated) | £1,300 to £1,995 | Median £1,550 |
| Exit fee | None on these files | 2 of 272 |
| All fees as a share of the loan | 3% to 5.2% | Fixed fees weigh most on small loans |
Three of the local files paid no valuation fee, and none paid an exit fee. Legal fees are estimates, and one solicitor acts for both sides under dual representation. Source: pooled Lendlord records.
Bidding on a Plymouth lot this month? Call Clare's bridging team on 020 8191 9611.
Plymouth prices and rents from official data
HM Land Registry recorded 3,107 standard sales in Plymouth from September 2025 to August 2026. The median price paid was £228,000. Terraced houses sold for a median £215,000, and homes in PL4 for £192,750.
The ONS puts the average Plymouth rent at £1,004 a month in August 2026, up 4.7% on a year earlier. Twelve months of that rent over the median price gives a rough 5.3% gross yield. That is our own sum, a screen and not a valuation.
Read the raw figures in HM Land Registry Price Paid Data and the ONS Price Index of Private Rents.
What Plymouth lets earn for Lendlord landlords
Rent and value recorded on 65 let Plymouth homes that Lendlord landlords own, next to the regional figure. Snapshot at 30 September 2026.
| Figure | Plymouth |
|---|---|
| Median rent a month | £850 |
| Middle half of rents | £650 to £1,050 |
| Gross yield | 6.9% |
| Median value | £170,000 |
| Share with a mortgage | 33% |
| Homes counted | 65 let, 86 owned |
Rent is the monthly rent recorded on each let home. Value is the owner's own estimate. The middle half runs from the 25th to the 75th percentile. Aggregated from Lendlord's own data.
The median Plymouth let earns £850 a month, under the ONS city average of £1,004. Half sit between £650 and £1,050.
The exit test further down uses the ONS terrace rent of £1,046. On the median rent here, 145% cover at a 5.5% stress rate supports about £128,000 of mortgage. Run the test on the rent your own tenancy will evidence.
How Plymouth homes rate on energy
Of 65,404 domestic certificates lodged in Plymouth from October 2016 to October 2026, 46.8% rated D or below.
- Band A
Share of certificates: 0.7% (440)
- Band B
Share of certificates: 10.3% (6,724)
- Band C
Share of certificates: 42.2% (27,617)
- Band D
Share of certificates: 36.1% (23,600)
- Band E
Share of certificates: 8.3% (5,440)
- Band F
Share of certificates: 1.8% (1,146)
- Band G
Share of certificates: 0.7% (437)
Your refinance exit, step by step
11 of 12 Plymouth bridges ended in a remortgage. Line up these steps ahead of the auction.
- Read the legal pack. Check the title, any short lease and the special conditions before you commit a deposit.
- Get indicative terms. Send us the lot number and guide. We size the bridge on price and planned works.
- Book the valuation early. The valuer needs access, so ask the auctioneer for a viewing slot in sale week.
- Price the works. A kitchen, a bathroom and rewiring is the usual Plymouth list. Get it quoted in writing.
- Brief a buy-to-let broker in month one. Most lenders want the works signed off and a tenant lined up. Some apply a six-month ownership rule.
- Refinance and repay. The mortgage clears the bridge. Repaying early cuts the interest you owe.
Would the remortgage clear each bridge?
We ran the four lots above through a standard buy-to-let rent test. Rent is the ONS average for a terraced house in the city, £1,046 a month. The new loan is the lower of 75% of value and what that rent supports at 145% cover on a 5.5% stress rate.
| Lot | Value after works | 75% of value | Loan after rent test | Bridge to repay | Result |
|---|---|---|---|---|---|
| PL2 unmodernised terrace | £185,000 | £139,000 | £139,000 | £105,000 | Clears, £34,000 spare |
| PL4 four-bed terrace | £170,000 | £127,500 | £127,500 | £85,000 | Clears, £42,500 spare |
| PL2 multi-let terrace | £250,000 | £187,500 | £157,500 | £110,000 | Clears, £47,500 spare. Rent sets the loan |
| PL3 long-underwrite terrace | £190,000 | £142,500 | £142,500 | Up to £90,000 | Clears, £52,500 spare |
Loan, value and interest terms from Lendlord's bridging book. Case figures are rounded to the nearest £5k. Rent: ONS Price Index of Private Rents, Plymouth terraced average, August 2026. Spare is before fees and legal costs. Rolled-up interest assumes the full term. The multi-let and flats lots would be tested on room or unit rents. Based on Lendlord aggregated data.
All 4 of 4 lots repay their bridging loan with room to spare. Rent capped the new loan on only 1, the multi-let. On the rest, the 75% value limit set it.
The line to watch is end value. At 145% cover, that terrace rent supports about £157,500 of mortgage. Above roughly £210,000 of end value, rent caps the remortgage before the 75% limit does. At 125% cover that line moves to about £245,000.
So on a bigger lot, price the exit on rent, not just the valuation. Lenders set the cover level by tax band and structure. See how lenders run the rent stress test before you bid.
How deep is Plymouth's remortgage market?
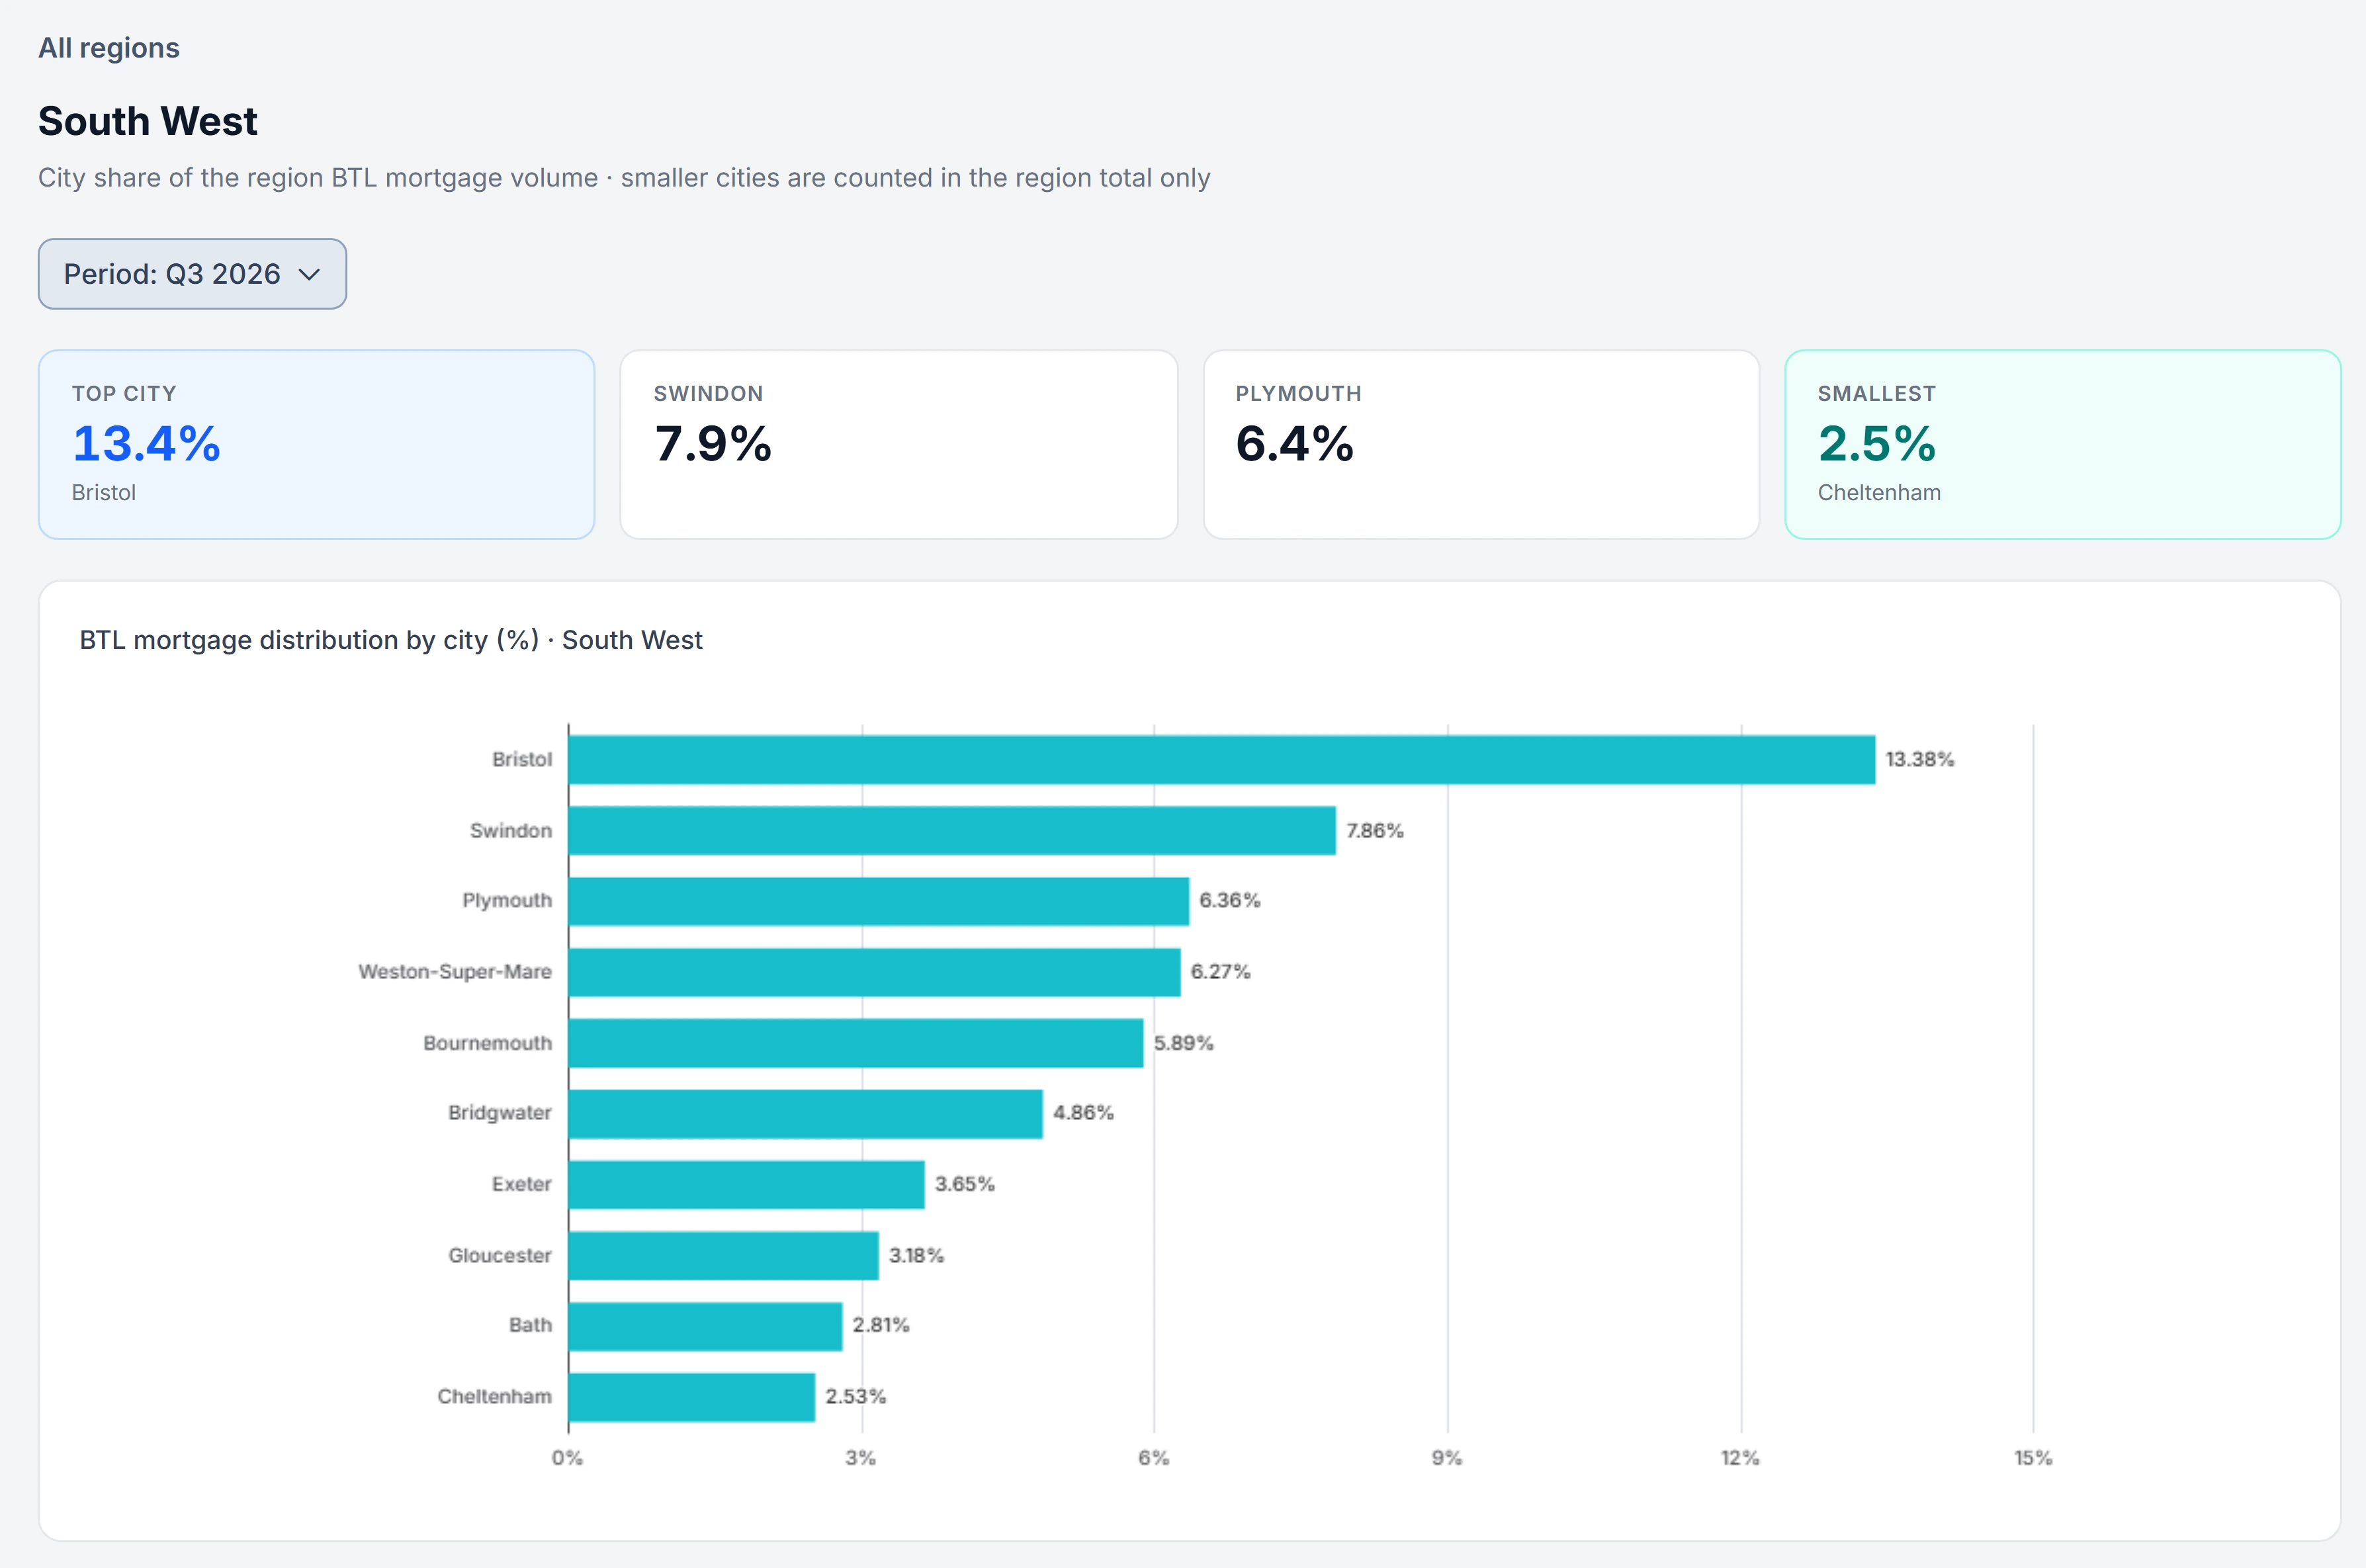
Share of South West buy-to-let mortgage volume by city, Q3 2026
This chart comes from the Lendlord BTL Market Report for Q3 2026. The report analyses anonymised landlord portfolio and mortgage data held on the Lendlord platform. It is a separate source from our bridging book.
Each bar is a city's share of every BTL mortgage recorded across the region that quarter. Smaller towns count towards the regional total but have no bar of their own. The region as a whole holds 5.24% of UK BTL mortgage volume in the same report.
Source: pooled Lendlord records.
What the chart means for your bridge
- Third in the region. Plymouth holds 6.36% of the region's BTL mortgages, behind Bristol at 13.38% and Swindon at 7.86%.
- Close to twice Exeter. Exeter sits at 3.65%. A larger local mortgage book usually means more let comparables for the valuer when you refinance.
- Brief the remortgage on day one. Ask your broker for the product, the rent the lender will stress test and the valuation they need. Then size the bridge so the new mortgage clears it in full.
Plymouth checks before you bid
Lead with the council rules if the plan is shared housing.
Paperwork to gather before a Plymouth auction
Send these with the application, not after the hammer falls. The legal pack and the valuation set the pace on these terraces.
Where Plymouth lots are sold
Calendars checked on 7 October 2026. Dates move, so confirm with the auctioneer.
Cynthia Nerih, an investor who funds auction buys through Lendlord, put the auction risk plainly on Instagram:
If you are crazy enough to buy property at auction… then you need Lendlord Capital. Don’t let finance be the reason you lose a deal after the hammer drops…
Plymouth districts in our files
Every Plymouth bridge sits in one of these postcode districts. PL4 carries the most.
- PL4: 5 deals
- PL1: 2 deals
- PL2: 2 deals
- PL3: 2 deals
- PL5: 1 deal
Rent and value figures above come from let homes recorded in Plymouth.
How Plymouth landlords used the bridge
Each line counts our Plymouth files of that type and links the full guide.
- Auction bridging (10 files)
- Bridging for a rental purchase (1 file)
- Refurbishment bridging (1 file)
- Unmortgageable property (5 files)
Guides for unmodernised auction terraces and the remortgage after
Most of our Plymouth loans follow one route: an auction terrace in PL1 to PL5, often unmodernised, then a remortgage onto a rental mortgage. Each guide below covers one stretch of that route. No other South West city page is live yet, so the nearest city page we link is Birmingham.
- Lending on a house you cannot mortgage yet: 5 of our Plymouth terraces were bought in that state.
- Bridging finance for an auction purchase: The product behind 10 of the 12 local deals.
- Choosing a refinance or a sale exit: 11 of the 12 here planned a remortgage exit.
- Test the remortgage ICR before you bid: Check the rent covers the new mortgage.
- What our auction-tagged deals show: Loan sizes, exits and timings across the UK.
- Birmingham bridging deals and terms: Our nearest live city page to Plymouth.
Verified Trustpilot reviews from Lendlord borrowers
Reviews from landlords who used Lendlord for finance. Reviewers are from across the UK, not only Plymouth.
Fantastic timely service from Lendlord.
“Fantastic timely service from Lendlord. Communications was timely throughout the process from Simmy and Fraser! We would recommend Lendlord without reservation, absolutely fantastic service!”
Leslie Burgess
Verified review on Trustpilot from Leslie BurgessBest in business
“I have used Lendlord mortage and remortgage services in the past and always with success and of course smooth process with weekly updates etc Simmy and Fraser always deliver great service and approach the right Lenders Highly recommend”
VG
Verified review on Trustpilot from VGAn asset to anyone looking for property based finance
“Lendlord offer a fantastic online platform which allows you to analyse and apply for various finance options easily (this is what first attracted me to them) that said what was more impressive is the ability to actually speak to a team who are extremely helpful and knowledgeable…”
Pizzazz Property Solutions
Verified review on Trustpilot from Pizzazz Property Solutions
Plymouth bridging questions
Who funds auction bridges in Plymouth?
Lendlord does. Most of our files here were auction terraces in PL4, and the fastest reached funds in 14 days.
Can I bridge a Plymouth auction lot with no kitchen?
Yes. All 5 such terraces we funded here had a remortgage exit, and 3 are already repaid. We lend on the purchase, and you refinance once the works are signed off.
How fast can a Plymouth bridge complete?
From 5 days on our current process. Among the 12 local files, the fastest took 14 days and the median was 52. If the contract gives you 28 days, apply before the sale.
What rate should I expect in Plymouth?
The median Plymouth rate was 1.04% a month. It moves with LTV, condition and exit, so ask for terms on the specific lot.
Clare Harris
Bridging Loan Specialist and Director of Growth at Lendlord · 12+ years in loans and lending · Checked every Plymouth file against the loan records
Last reviewed
How we built the Plymouth figures
The table holds each local loan in the 272 disclosed deals, funded November 2023 to January 2026. Plymouth clears our 10-deal bar, so the medians here are city figures.
Speed is days from application to funds. Records flagged as timeline outliers, or showing zero days, stay out of speed figures. We show postcode districts and funded years only, with loans rounded down to the nearest £5k.
Product terms, such as funding from 5 days, describe how we work today. Every local figure describes these files as they were funded.
Bidding on a Plymouth lot this month?
Send us the lot and guide price. Clare's team will come back with indicative terms and the exit we need to see.
Who provides the service
Lendlord Limited, company 11973095, runs the landlord software. The registered office is Churchill House, 137-139 Brent Street, London, NW4 4DJ. The public name is Lendlord.
Lendlord Finance Limited, company 13696524, uses the trading name Lendlord Capital for bridging. It lends that loan itself. Mortgage and remortgage applications are a separate service.
Lendlord Finance Limited arranges those mortgages as an appointed representative of Windfall Limited. The FCA authorises Windfall Limited under firm reference 225908. The mortgage itself comes from a lender on that panel.
Lendlord Limited is registered for account information services, so a bank feed can be read with your consent. That registration is not permission to lend, and it is not permission to arrange a mortgage.
Bridging on this page is secured on property in England and Wales. Lending here goes up to 80% LTV. A below-market buy can still reach 90% of the purchase price.