Will this BTL remortgage clear cashflow on today's rates?
Published · Updated
5 min read
Will the new payment still leave cash?
Yes, on this file. A £182,000 interest-only loan at 70% of value costs £9,555 a year at an illustrative 5.25% pay rate. Rent of £1,250 pcm covers that. About £234 a month is left before tax.
That 5.25% is a worked example, not a product on offer today. The lowest rate on Lendlord's Q3 2026 buy-to-let book is 4.13%, so this case sits above the cheapest print. Swap in the rate you can reserve, then rerun the same lines.
Stamp duty is £0 when the same owner stays on the title. A move into a company is a purchase, not a remortgage.
Pay rate set as an illustration on 13 October 2026. Lending goes up to 80% LTV on that date. Repayment share, lowest rate and LTV shares are from the Lendlord BTL Market Report, Q3 2026.
The remortgage, line by line
The property is a personally owned two-bed, already let. Value is £260,000. The new loan is £182,000, which is 70% of that value. The product is a five-year fix with no capital repayment, so the monthly figure has no capital repayment.
| Line | A month | A year |
|---|---|---|
| Rent received | £1,250 | £15,000 |
| Interest at 5.25% | £796 | £9,555 |
| Left after the interest | £454 | £5,445 |
| Running costs set aside | £220 | £2,640 |
| Cash before tax | £234 | £2,805 |
Interest is £9,555 a year, or £796.25 a month. Monthly rows are rounded. The £220 is an allowance for insurance, repairs and a letting agent, not a quote.
Treat £234 as cash in the bank, not profit after tax. The finance-cost credit does not change what the lender takes each month.
Add a 1% product fee (£1,820) to the balance and the loan becomes £183,820. Interest rises to about £9,651 a year, near £804 a month. Cash before tax is still about £226. The fee is a slightly bigger loan. You feel it on the payment.
Before you reserve
Swap 5.25% for a live product
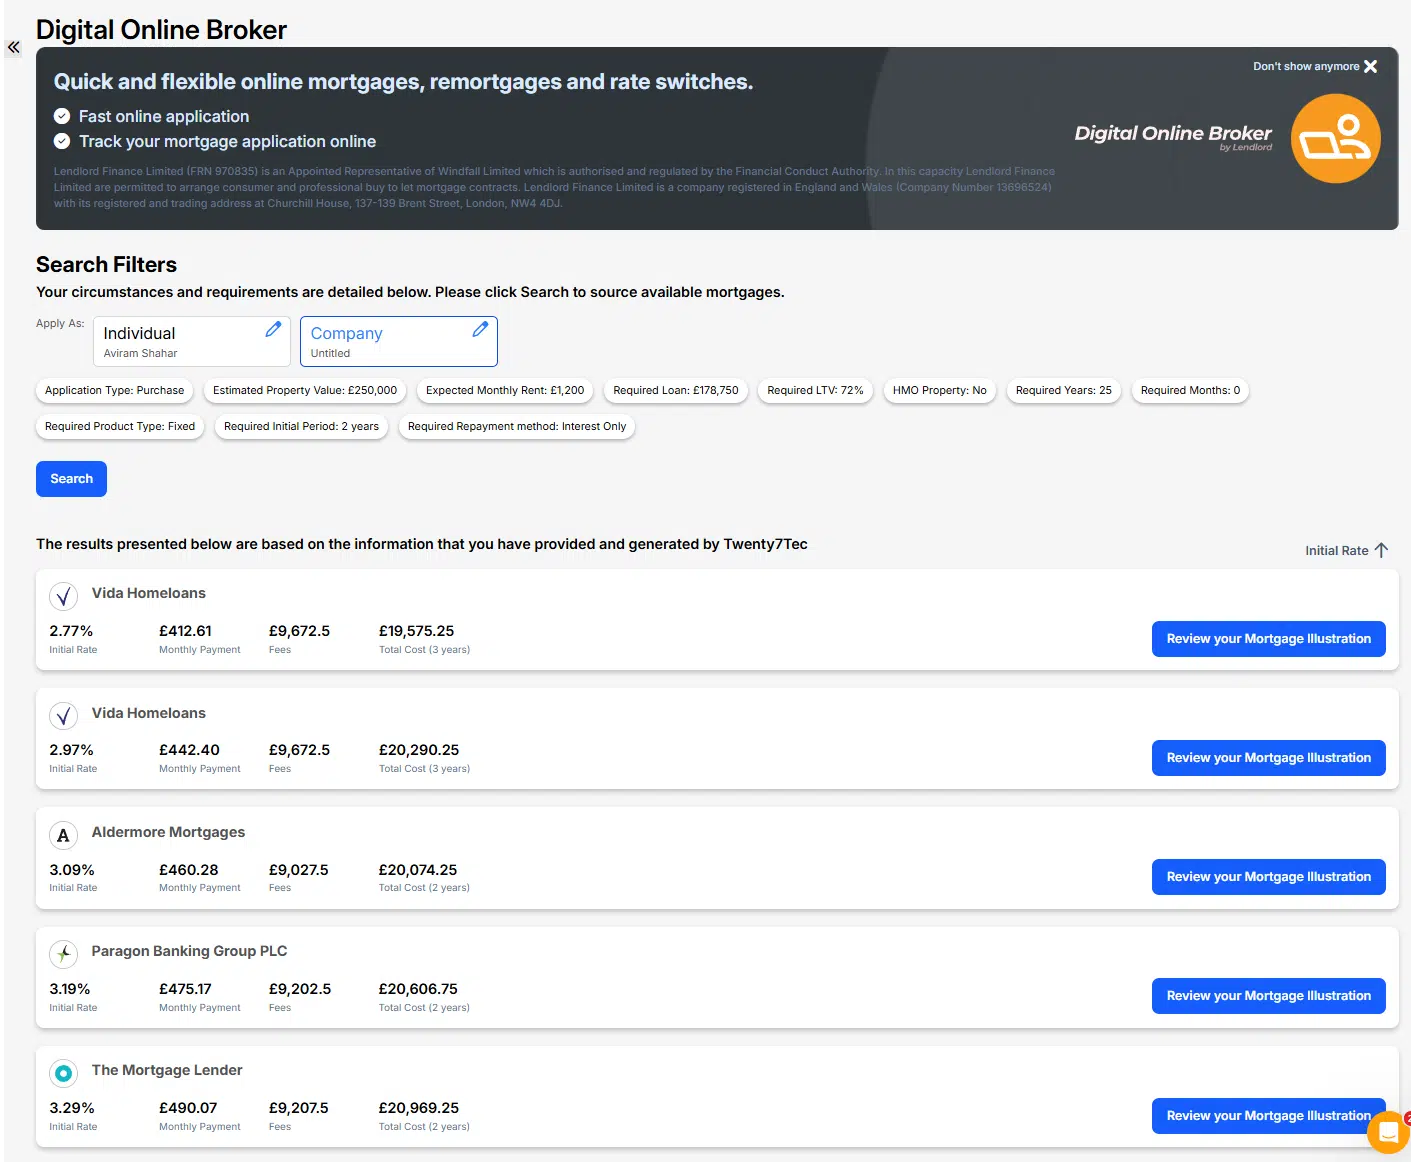
The cash line above uses an example rate. A product you can hold may be higher or lower. Rerun the payment on that rate.
See live mortgage productsMost small portfolios do not repay capital
This file matches how small portfolios are actually written. In the Q3 2026 report, 83.2% of mortgages in the 1 to 3 property band are interest-only. A repayment loan would take more cash each month than the table shows.
Leverage on the book is mostly lower. Only 9.7% of properties sit above 75% LTV, and only 3.5% of portfolios do. This 70% file sits in that usual band.
Lendlord can lend up to 80% LTV. On this £260,000 value that is £208,000. Interest at 5.25% is £910 a month. Cash before tax is £120. The higher loan still needs the rent to cover the payment and to pass the stress test.
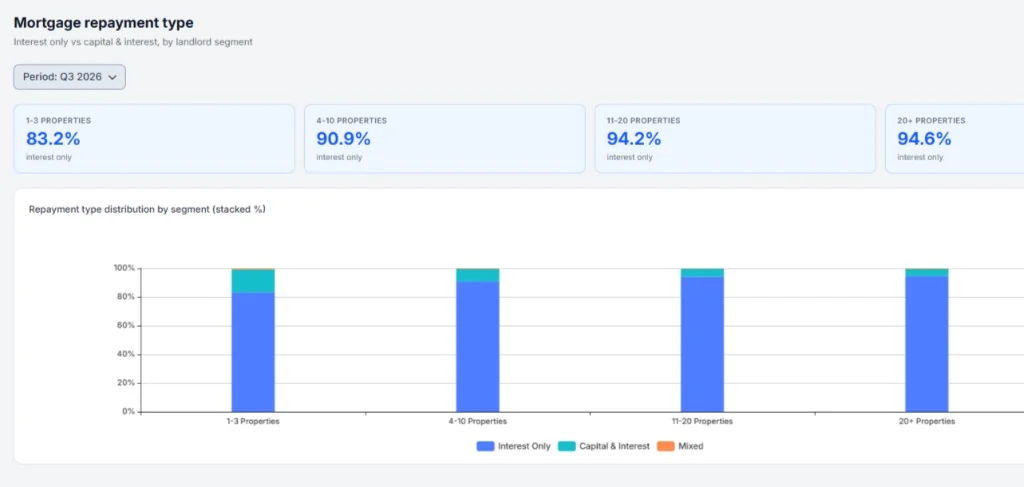
Source: Lendlord buy-to-let market research hub, Q3 2026 repayment type by segment.
What you pay to refinance
A product transfer with your current lender is often the smaller job. You stay on the title. Many transfers skip a new solicitor and a new valuation. The stamp line stays at £0.
A full move to a new lender can add legal work and a valuation. Treat those as a one-off. Do not bury them in the monthly cash line unless you choose to spread them.
The workshop below is the product conversation: what is on offer, and how one case was written. Keep the £234 line above as the cash test for this loan.
Products and one worked case
Before you reserve the product
- Confirm whether each payment includes capital. A capital repayment costs more each month than this example.
- Ask if the product fee is added to the balance. Rerun the payment on the higher loan.
- Keep the same owner if you want stamp duty at £0. A transfer into a company is a purchase.
- SDLT is charged on a purchase. Scotland and Wales use their own land tax. A plain remortgage is still not a purchase.
- Rerun the rent at a lower figure before you rely on the £234.
Cash after the pay rate is your question. The lender asks a harder one. ICR tests the rent against a stressed rate, not against 5.25%. Use the ICR stress test for that pass or fail. If the fix ends soon, start with loans that end inside a year.
If the rent is thinner
Rerun the same loan at £950 pcm. Interest is still about £796. The £220 cost allowance is still there. You are about £66 short each month. The same rent at 80% LTV is £180 short. Cutting the allowance to force a pass only hides repairs you will still pay.
A repayment mortgage would miss by more. Part of each payment is capital, and that capital is not in this example. Match the repayment type before you trust the £234.
Drop today's rate into the same table
Take the pay rate on the product you can reserve, not the rate the loan reverts to later. Multiply the loan by that rate. That result is the yearly interest. Divide by 12 for the month.
Subtract it from the rent you actually receive. Then subtract a cost allowance you believe, not a round number chosen to make the line positive. If the fee is added, use the higher balance.
Keep the result only when cash stays positive and the stress test still passes. One without the other is not a completed remortgage.
Use your rent and your loan
Change the rate, the fee and the rent. Keep going only if cash stays positive, then run the stress test.
Run this rent and loan
Expert insight from Simmy Kaur, Director of Buy to Let Mortgages · Financial Reporter's 30 Under 30 2025 · Last updated October 2026
On a remortgage the first number I want is cash after the new payment, with the fee on the balance. If that line is negative, a cheaper product transfer will not save the case. If it is positive, the stress test is the next gate.
Official data sources
- Stamp Duty Land Tax: when you buy property or land
- Lendlord BTL Market Report, Q3 2026: repayment type by segment, lowest interest rate, and property LTV above 75%
- The 5.25% pay rate, the £220 cost allowance and the £1,250 rent are an anonymised illustration, not a lender offer