89% of Buy-to-Let Mortgage Searches Ask for Interest Only
Published
5 min read
89% of 2,788 Live Products searches approved for disclosure asked for interest only in the 90 days to 30 September 2026. Interest only means the monthly payment covers interest and the balance stays in place.
A search is a request for products, not a completed application. The figures below are what people typed, not what a lender offered.
Figures last checked on 30 September 2026. Searches from 3 July to 30 September 2026.
What searchers ask for
Capital and interest is the minority choice, at 10.2% of the same 2,788 searches. The typical request is a £140,000 loan at 75% LTV, on a £204,000 property, with £1,200 rent.
| Field | Figure |
|---|---|
| Interest only | 88.6% |
| Capital and interest | 10.2% |
| Requested LTV | 75% |
| Loan | £140,000 |
| Rent | £1,200 |
| Property value | £204,000 |
Source: 2,788 Live Products searches approved for disclosure, 90 days to 30 September 2026. Loan, rent, value and LTV are medians. This is not the UK mortgage market.
The exact share is 88.6%. Capital and interest means each payment also reduces the balance. Requested LTV is the loan to value the searcher typed, the loan as a share of the value.
58.5% of the searches were purchases, and 24.2% named a company as the borrower. If your own loan or rent is far from these medians, treat the 88.6% as a habit among searchers, not as a fit for your case.
Companies, HMOs and standard lets
HMO means a house in multiple occupation. Company searches and HMO searches ask for interest only more often than private borrowers and standard lets. The requested LTV stays at 75% in every row.
| Group | Searches | Interest only | Requested LTV |
|---|---|---|---|
| Company | 675 | 94.8% | 75% |
| Private borrower | 2,113 | 86.6% | 75% |
| HMO | 196 | 92.3% | 75% |
| Standard let | 2,592 | 88.3% | 75% |
Source: Live Products searches, 90 days to 30 September 2026. Company and private are the borrower. HMO and standard let are the property type.
Capital and interest is 4.9% of company searches and 11.8% of private ones. An HMO search also asks for more rent and a larger loan: median rent £2,800 and loan £240,000, against £1,100 and £134,148 on a standard let. That is a different deal. It is not advice to pick interest only.
Your search
Enter your own loan and LTV
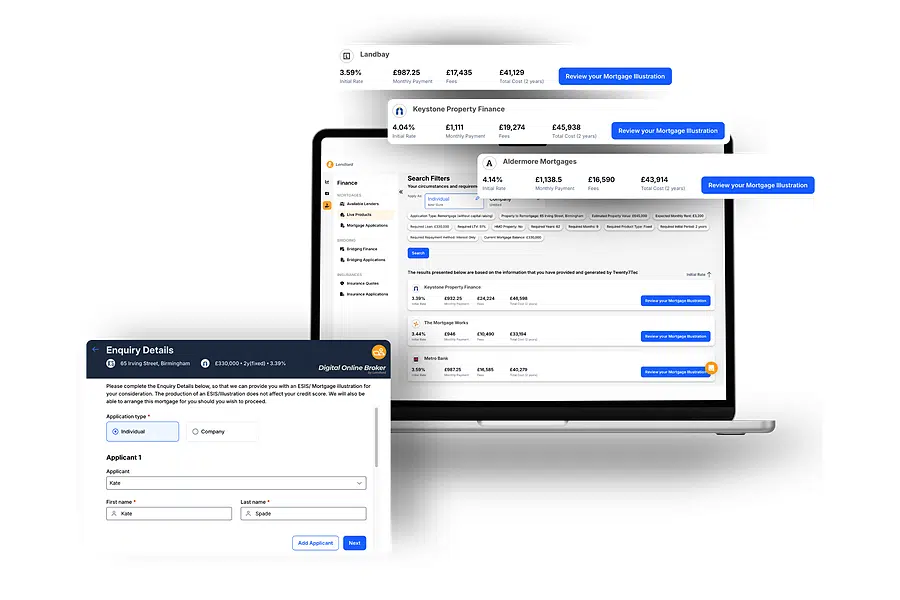
Live products list what is on offer once the loan, value and repayment type are filled in.
Open live mortgage productsWales is the exception
Wales is the only nation cut quoted here, and it is a small one: 48 searches. Interest only falls to 62.5%. Mixed repayment, part interest only and part capital and interest, is 35.4%. Capital and interest alone is 2.1%.
The requested LTV is 65.6%, not 75%. The median loan is £88,500, rent £800, value £135,000. Do not treat 48 searches as a national habit. Do treat them as a reason to ask why a lower LTV and a mixed payment showed up together.
Interest only on £140,000
One month at 5.5%
The median loan in these searches is £140,000. At an illustrative 5.5%, monthly interest is the balance times 5.5%, divided by 12. That is £641.67 a month.
At the end of the term the balance is still £140,000, because interest only does not repay capital. A repayment loan would shrink that balance. These searches do not record that monthly repayment figure.
Rent still has to cover the lender's stress test, which is a higher rate than the pay rate. Use the rent cover test lenders run, then your own monthly figure on your balance, not only on £140,000.
Rates and the repayment choice
When repayment or part-and-part fits
Questions to ask before you copy the 88.6%
These are checks, not a product recommendation.
- How will the £140,000 of capital, or your own balance, be repaid when the term ends?
- Does the rent still cover the loan at the stress rate, not only at 5.5%?
- What loan to value is left if the value is lower at the end of the term?
- Has an accountant checked the tax treatment of finance costs on a personal borrower?
A worked remortgage, including whether the new payment clears, is in a worked remortgage. Speak to a broker before you pick interest only because most searches do. Speak to an accountant before you assume the interest is treated the same way on a personal name as in a company.
Questions on interest only
What share of buy-to-let searches ask for interest only?
88.6% of 2,788 searches, which rounds to 89%. Company searches are 94.8% interest only. HMO searches are 92.3%. Standard lets are 88.3%.
What loan and LTV do people enter?
The median request is a £140,000 loan, £1,200 rent and a £204,000 value, at 75% LTV. A standard let is close to that, at £134,148 and £1,100 rent.
Why is Wales different?
In 48 Welsh searches, interest only is 62.5% and mixed repayment is 35.4%. Requested LTV is 65.6%. The count is small, so read it as a prompt to ask, not as a rule for Wales.
Does interest only leave the loan unchanged?
On the £140,000 example at 5.5%, the month costs £641.67 and the balance at the end is still £140,000. You need a separate plan for the capital.
These figures are Live Products searches approved for disclosure, not completed mortgages and not the UK market. The window is 3 July to 30 September 2026, 90 days. The count is 2,788. Searches are not linked to accounts, so one person can appear more than once. A search records a request, not an offer.
Other areas are too small to quote. Wales is included at 48 searches and should be read as thin. The 5.5% rate is an illustration, not a median rate from the searches.
Ask where the capital will come from before you copy the search habit. Interest only keeps the payment down but leaves the full loan to repay. A broker can price both. An accountant should look at the finance-cost position if you borrow personally.
Put your balance next to a live rate
See both repayment types on your own loan before you decide.
Compare a repayment type
Expert insight from Simmy Kaur, Director of Buy to Let Mortgages · Financial Reporter's 30 Under 30 2025 · Last updated October 2026
Official data sources
- FCA handbook: regulation of buy-to-let lending. Linked for the consumer buy-to-let framework. No FCA figure is quoted here.
- GOV.UK: tax relief for residential landlords. Linked because finance-cost relief is an accountant question. No tax figure is quoted here.