BTL Stress Test and ICR Calculator: Check Affordability Before You Remortgage
Published · Updated
5 min read
A buy-to-let stress test checks whether rent covers mortgage interest at a higher hypothetical rate, usually from about 5.5%. Most personal basic-rate and limited-company cases use about 125% ICR. Higher-rate personal cases often need 145%.
This guide is for UK landlords who need a clear BTL stress test and ICR calculator before a remortgage or new purchase. You get an interactive calculator, lender band tables, worked examples, and Q3 2026 Market Report rate context for private and company ownership.
What landlords are paying right now
| Ownership | Average rate |
|---|---|
| Private landlords | 4.76% |
| Company-owned portfolios | 6.44% |
| Company, 11-20 property segment | 9.66% |
Private landlords still pay less than company landlords on average. Source: Lendlord BTL Market Report, Q3 2026.
Company landlords pay 1.7% more on average
About 1.7 percentage points more than private landlords. Source: Lendlord BTL Market Report, Q3 2026. That gap is costing portfolio landlords thousands a year. Compare live products against what you pay now.
Compare my ratesAt a glance
- Stress test: Rent must cover interest at a stressed rate, not only the pay rate.
- Typical ICR: About 125% for basic-rate and Ltd cases; about 145% for many higher-rate personal cases.
- Rate context: Private averages 4.76%; company averages 6.44% (Q3 2026 Market Report).
- Urgency: 39.0% of BTL mortgages expire within 12 months; 55.2% for 20+ portfolios.
- Next step: Pass the calculator, then compare live products before your fix ends.
Don't wait on the next remortgage window
Live products
Move from calculator assumptions to real lender options
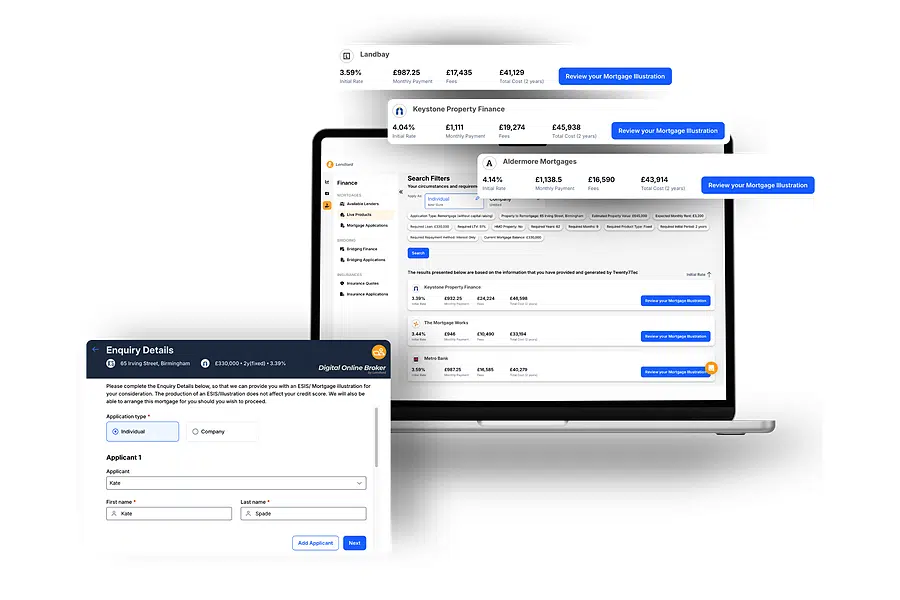
After you pass a stress test, compare live BTL products for private and limited-company borrowers.
Compare live mortgage productsRate figures last checked August 2026. Source: Lendlord BTL Market Report, Q3 2026.
What a BTL stress test actually checks
Lenders do not only ask whether rent covers today's interest. They ask whether rent still covers interest if rates were higher.
That higher figure is the stress rate. Interest coverage ratio (ICR) is how much rent must exceed that stressed interest. Fail the test and the loan size usually has to fall, or the product changes.
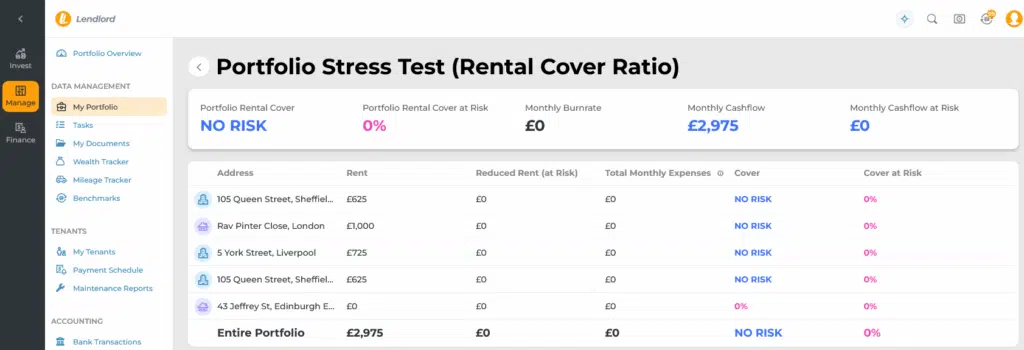
See a live deal stress test
Run the ICR calculator
Enter rent, loan, stress rate, and ICR band. The tool shows pass or fail, required rent, and an indicative maximum loan.
BTL stress / ICR calculator
Check whether rent covers stressed interest at common UK lender bands.
Indicative max loan
£180,564
Rent headroom (a year)
£45
Pass at 145% ICR
Your rent clears the 145% ICR requirement at a 5.5% stress rate.
Breakdown
- Stressed interest (a year)
- £9,900
- Required rent (a year)
- £14,355
- Your rent (a year)
- £14,400
Guidance only. Your lender may use different rules. Pair results with live quotes.
Uses common lender rules for guidance. Rate averages from the Lendlord BTL Market Report, Q3 2026.
ICR and stress bands landlords use
| Borrower type | Typical ICR | Typical stress rate |
|---|---|---|
| Basic-rate taxpayer (personal) | 125% | 5.5% to 8% |
| Higher-rate taxpayer (personal) | 145% (some to 160%) | 5.5% to 8% |
| Limited company BTL | 125% | 5.5% to 8% (often pay-rate on 5-year fixes) |
| HMO / complex | 175% (common) | 5.5% to 8% |
Typical lender bands for guidance. Always check the product you apply for.
Worked ICR examples
Pass: basic-rate personal
Rent £1,200 pcm. Loan £180,000. Stress 5.5%. ICR 125%.
Stressed interest £9,900 a year. Required rent £12,375. Actual rent £14,400. Result: pass, with about £2,025 headroom.
Simple example using a 125% ICR and 5.5% stress rate.
Fail: higher-rate personal
Rent £1,000 pcm. Loan £180,000. Stress 5.5%. ICR 145%.
Required rent rises to £14,355. Actual rent £12,000. Result: fail. Options include a lower loan, stronger rent evidence, or a 5-year fix with softer stress.
Same method, with the 145% ICR many higher-rate landlords face.
Company rate gap cost
On a £250,000 interest-only loan, private average 4.76% costs about £11,900 a year. Company average 6.44% costs about £16,100.
Gap: about £4,200 a year on the same balance. Compare live company products before you assume the average.
Based on average rates from the Lendlord BTL Market Report, Q3 2026.
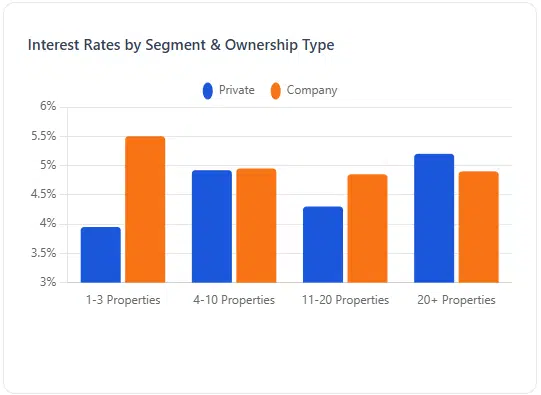
Private vs company ownership gap
The rate snapshot shows the pay-rate gap. Ownership share explains why that gap hits portfolio landlords hardest.
| Metric | Private | Company |
|---|---|---|
| Share of UK BTL ownership | 54.9% | 45.1% |
| Share among 20+ property landlords | 42.4% | 57.6% |
| Average mortgage rate | 4.76% | 6.44% |
Who owns what, and what they pay. Source: Lendlord BTL Market Report, Q3 2026.
The gap between the average private rate at 4.76% and the average company rate at 6.44% is the clearest saving opportunity in the whole dataset.Simmy Kaur, Director of Buy to Let Mortgages at Lendlord
Mortgage broker
Stress-test first, then compare the whole market
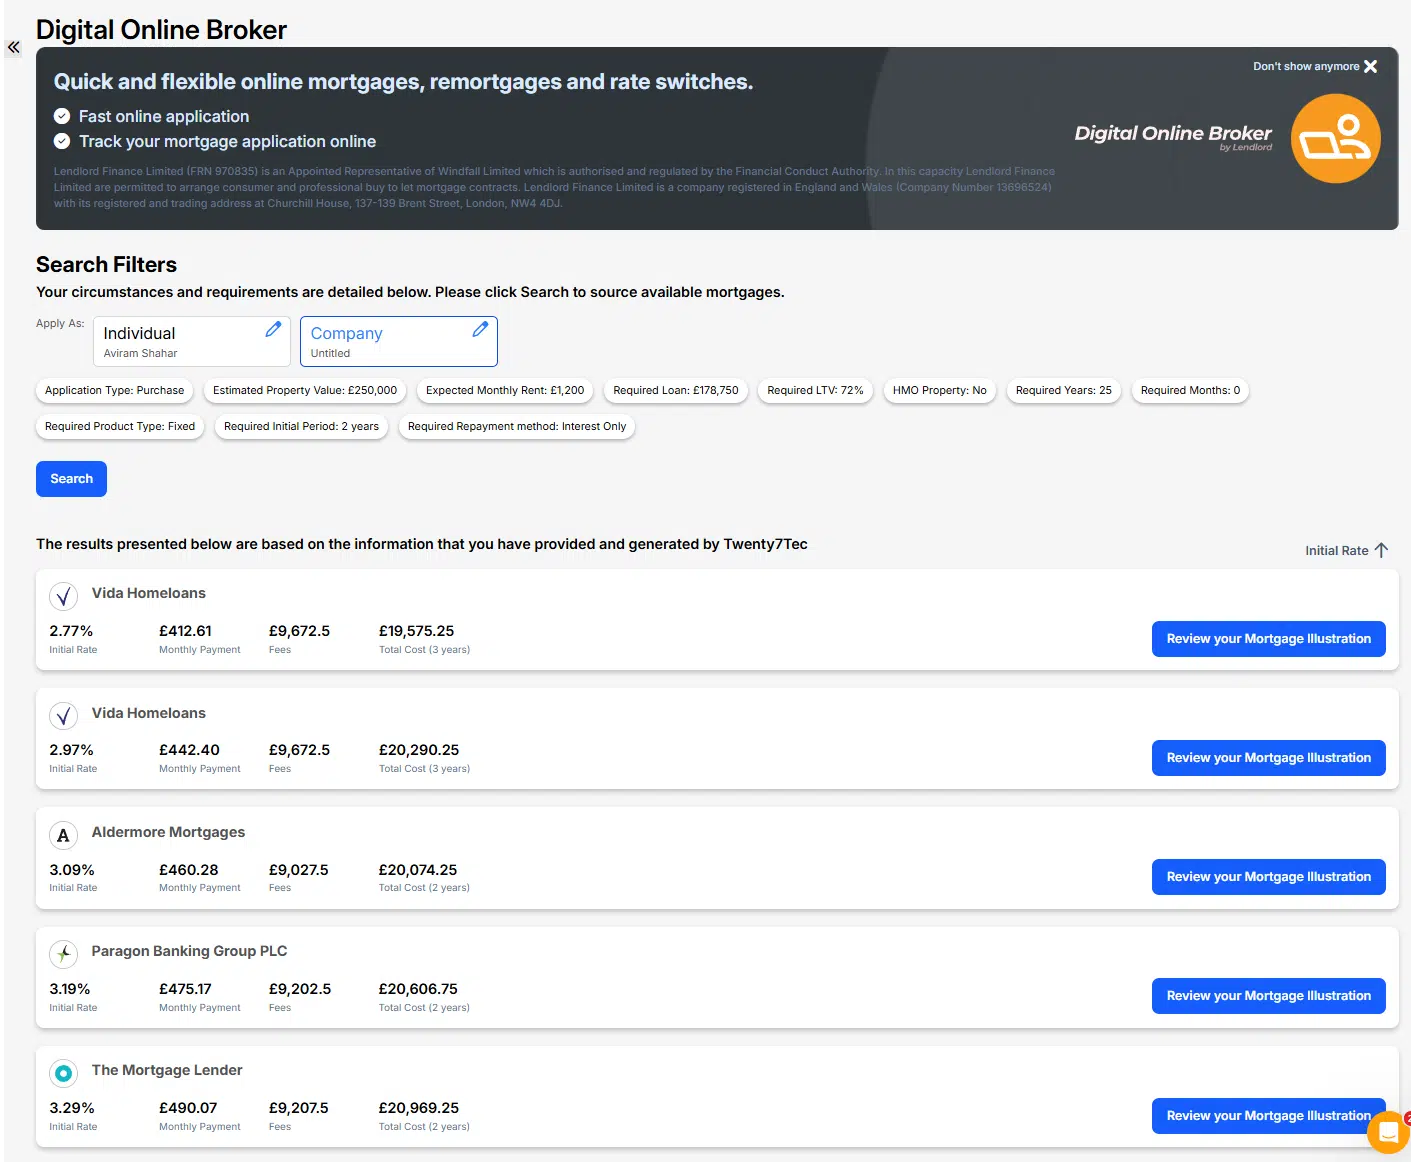
Santander, The Mortgage Works and Aldermore hold about a third of the BTL book. Two thirds sits with lenders many landlords never compare.
Open the online mortgage brokerWhy stress tests matter before your fix ends
39.0% of BTL mortgages expire within 12 months. For landlords with 20 or more properties, 55.2% expire within a year.
Source: Lendlord BTL Market Report, Q3 2026.
39% of BTL mortgages expire within twelve months, and for landlords with twenty or more properties it is over half. Most portfolios have a repricing event closer than their owners think.Simmy Kaur, Director of Buy to Let Mortgages at Lendlord
39% of BTL mortgages expire within a year. Is yours one of them?
Source: Lendlord BTL Market Report, Q3 2026. Track expiry dates and stress-test the next product before your fix ends. If timing gets tight, plan the refinance early.
Check my expiry datesFrequently asked questions
What ICR do buy-to-let lenders use?
Most lenders look for rent to cover stressed interest at about 125% ICR for basic-rate and limited-company borrowers, and often 145% for higher-rate taxpayers. Always check the specific lender. Run your numbers in the calculator above, then browse live lender options.
What is a BTL mortgage stress test?
Lenders test whether rent still covers the mortgage at a higher hypothetical rate, often from 5.5% upward, not only at the pay rate you will actually pay. Use the stress rate field in this guide's calculator before you apply.
Do limited company landlords pay higher mortgage rates?
In Lendlord's Q3 2026 Market Report, company portfolios averaged 6.44% versus 4.76% for private landlords. That gap is why company landlords should stress-test and compare specialist products, not assume the private average.
How many BTL mortgages expire within a year?
39.0% of BTL mortgages expire within 12 months. Among landlords with 20 or more properties, 55.2% expire within a year. Stress-test the next product before your fix ends via Lendlord's online mortgage broker.
Next step after you pass
Save your calculator inputs. Match them to a live product. Then remortgage or purchase with criteria you already passed on paper.
Run the stress test, then compare products before your fix ends.
Compare BTL mortgage options
Expert insight from Simmy Kaur, Director of Buy to Let Mortgages · Financial Reporter's 30 Under 30 2025 · Last updated August 2026
Director of Buy to Let Mortgages at Lendlord. Advises landlords on mortgages, remortgages, portfolio lending, and lender comparisons. This ICR guide pairs lender stress norms with Lendlord BTL Market Report rate context.
Official data sources
- Lendlord BTL Market Report, Q3 2026 (ownership shares, average rates, mortgage expiry horizons, lender concentration)
- Industry lender norms for ICR and stress-rate bands (education only; confirm product criteria)
- Lendlord UK buy-to-let market research hub