Sandwell Bridging Finance for Lots That Need Works First
You win a Smethwick or Tipton house with no kitchen. No mortgage lender will touch it yet. 4 of our 6 Sandwell bridges started exactly there.
Sandwell · 6 deals · February 2024 to April 2026
4 of 6Sandwell lots had no working kitchen or water
Six deals is under the 10-deal bar. The counts below are these files.
Current terms
Bridging now goes up to 80% LTV
From 13 October 2026, Lendlord bridging goes up to 80% LTV. A below-market buy can still reach 90% of the purchase price.
What the Sandwell files show
Sandwell has 6 deals, under the 10-deal bar for a median. The counts are this city's own files. Based on Lendlord aggregated data.
- 6
- Sandwell deals among the 272 disclosed
- 5
- Auction purchases in this set
- 4
- Unmodernised or major works
- £190k to £205k
- Loan range, rounded to £5,000 (identifying loans left out)
Where the regional medians sit
Median loan, rate, LTV and days to funds for the West Midlands are on the West Midlands bridging loans page. This page keeps the Sandwell deals, and does not repeat those medians.
Two Sandwell lots
Source: pooled Lendlord records.
Auction · refinance
£190,000 at 65% LTV
- £190,000
- Loan
- 65%
- LTV
- 1.07%
- Rate pm
- 32 days
- Completion
- Bought for £215,000 with £10,000 of works. The figure after works is £400,000.
- Funded in 32 days in 2026 at 1.07% a month. The bridge is still live.
Funded 2026 · 12-month term · Refinance · Live
Auction · higher LTV
£205,000 at 90% LTV
- £205,000
- Loan
- 90%
- LTV
- 1.04%
- Rate pm
- 32 days
- Completion
- The loan is £205,000 against a £230,000 purchase. Works are £10,000, and the file shows £360,000 after the works.
- Also funded in 32 days, at 1.04% a month. At 90% LTV there is less equity if the works slip.
Funded 2026 · 12-month term · Refinance · Live
Bidding on a Smethwick or Wednesbury house with no kitchen? Ring Clare's team on 020 8191 9611 before the auction.
Why works-first lots need a bridge
A mortgage valuer marks a house with no kitchen or bathroom as unmortgageable. That rules out a buy-to-let loan on day one. The bridge pays for the purchase, then the works, and the mortgage comes last.
On a Sandwell lot the works usually come before a lender will value the house.
Price the works before you bid. An under-priced job stretches the term, and every extra month adds interest.
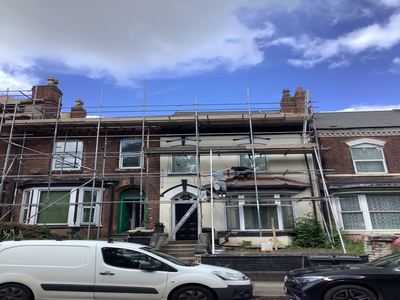
Days from application to funds on each Sandwell loan
The fastest file funded in 12 days and the slowest in 137. Both WS10 terraces took 32 days. One timeline outlier is left out.
- 2025 Auction
Days to funds: 12 days
- WS10 2026
Days to funds: 32 days
- WS10 2026 (2)
Days to funds: 32 days
- 2026 Auction
Days to funds: 53 days
- 2026 Buy-to-let
Days to funds: 137 days
Regional mix
Purpose, condition and loan size for the region are charted once, on the regional bridging page.
Based on Lendlord aggregated data.
All 6 Sandwell loans
6 rows. Loans are rounded down to £5,000 and the year is the only date. A district that would identify the house is marked Not shown.
| District and type | Funded | Purpose and condition | Loan | Exit |
|---|---|---|---|---|
| Not shown | 2024 | Auction, unmodernised | Over £100,000 | Refinance |
| Not shown | 2025 | Auction, unmodernised | Over £100,000 | Sale |
| Not shown | 2026 | BTL, unmodernised | Over £100,000 | Refinance (live) |
| Not shown | 2026 | Auction, unmodernised | Over £100,000 | Refinance |
| WS10 terrace | 2026 | Auction, not recorded | £190,000 | Refinance (live) |
| WS10 terrace | 2026 | Auction, not recorded | £205,000 | Refinance (live) |
Not timed marks a timeline outlier, kept out of every speed figure. Unmodernised: no working kitchen or running water at purchase. Exits are repaid unless marked live. One row: timeline outlier, excluded from speed figures. One row: LTV above the 75% cap in place when it funded. Source: pooled Lendlord records.
Gross LTV on the six Sandwell loans
Five of the six loans sat at 75% gross LTV or lower. One WS10 terrace funded at 90%, above the 75% cap in place at the time.
| Gross LTV | Files | Refinance exit | Sale exit |
|---|---|---|---|
| 61% to 70% | 2 | 2 | 0 |
| 71% to 75% | 3 | 2 | 1 |
| Over 75% | 1 | 1 | 0 |
Today we lend up to 80% LTV, or 90% of the purchase price on a below-market buy. Aggregated from Lendlord's own data.
Coal, licensing and the register in Sandwell
Sandwell sits on the Black Country coalfield. Start with the ground.
Lending criteria for a Black Country works-first lot
In Sandwell the ground and the exit matter more to us than the state of the kitchen.
Plan the exit before the works start
5 of the 6 Sandwell bridges are set to exit by refinance, and 1 sold.
- Fix the works scope. Kitchen, bathroom, heating and electrics are the usual minimum for a mortgage valuer.
- Pick the exit now. Sale or refinance changes the term we offer and the buffer we want.
- Hold cash for overruns. Houses this old rarely come in on budget.
- Book the sign-off. Building control and an EICR help the refinance valuer see a finished home.
- Line up the tenant or the buyer. A signed tenancy helps a buy-to-let valuation. A sale needs the agent in early.
Will the rent clear a typical Sandwell bridge?
Roll £140,000 up at 1.05% a month and a year later about £157,500 is owed. Fees are not in that figure.
Multiply £157,500 by 145%, then by 5.5%, then divide by 12. A lender would want about £1,050 a month. West Bromwich lets record £890, which covers about £134,000, and that falls short of the amount owed.
Based on Lendlord aggregated data.
Test a Sandwell let on yield and cash flow
Start with what Lendlord landlords' homes in West Bromwich show: a £200,000 value and £890 a month. Then enter your own deposit and watch the yield and ROI move.
Gross rental yield
7.37%
Monthly cash flow
£663
Where the rent goes
- Rent
- £1,750 pcm
- Mortgage interest (4.5%)
- £802 pcm
- Running costs (0.1% of value)
- £285 pcm
Over a year
- Rental income
- £21,000
- Cash flow
- £7,961
- Return on cash invested
- 11.17%
The numbers stack up
The rent covers the interest and running costs with something left over. Run the full analysis before you commit.
Indicative only. Interest-only at 4.5% and running costs of 0.1% of the property value a month stand in for your real quotes, and stamp duty, purchase costs and tax are left out. The Deal Analyser extension runs the full figures against the actual listing.
Advertised terms vs the Sandwell loans
Headline terms are best case. The 6 Sandwell loans show the real spread.
| Headline term | Local files | 272 disclosed bridging deals |
|---|---|---|
| Funding from 5 days | Today's process can fund within 5 days. AI checks your ID and bank statements in minutes, one solicitor acts for you and the lender, and loan papers are drafted automatically. On the files as funded, the fastest took 12 days. | Fastest 2 days. 2 of 218 timed deals within 7 days. Median 57 days |
| From 0.75% pm | 0 of 6 at or below 0.75%. Lowest 0.79% (2024) | 5 of 272, none since 2025. Since 2025: lowest 0.92%, median 1.10% |
| Up to 80% LTV | Highest gross LTV on these files 90% | The cap is now 80% of value. A below-market buy can still reach 90% of the purchase price. |
| Loans from £30k | Smallest £190,000, largest £205,000 (one larger site loan not shown) | £30k is the current product floor |
One Sandwell loan went above the 75% gross LTV cap in place when it funded. New loans go up to 80% LTV. Source: pooled Lendlord records.
Fee lines on the Sandwell loans we can show
Full fee detail is recorded on two of the six Sandwell files. Both paid a 2% arrangement fee.
| Fee | Local files | 272 disclosed bridging deals |
|---|---|---|
| Arrangement fee | 2% of the loan | Median 2% |
| Valuation fee | £195 to £495 | Median £495 |
| Lender admin fee | £990 | Median £795 |
| Lender legal fees (estimated) | £1,995 | Median £1,550 |
| Exit fee | None on these files | 2 of 272 |
| All fees as a share of the loan | 3.6% to 3.7% | Fixed fees weigh most on small loans |
Two files is a thin base, so read them next to the median for the 272 recent Lendlord bridging deals approved for disclosure. Neither local file paid an exit fee. Aggregated from Lendlord's own data.
Run the numbers on a Sandwell lot
Add the works to the loan if you need them funded.
Indicative monthly rate
0.82%
Monthly interest
£2,050
Cost of the loan
- Total interest
- £24,600
- Arrangement fee (2%)
- £5,000
- Valuation fee
- £750
- Legal fee
- £1,500
- Admin fee
- £350
- Total cost of finance
- £32,200
Day one and exit
- Net advance on day one
- £245,000
- Gross loan repayable at exit
- £274,600
Low risk - best pricing
At or below 50% LTV you qualify for our lowest rate band and the fastest underwriting.
Month-by-month repayment schedule
| Month | Interest | Balance | Cost to redeem |
|---|---|---|---|
| 1 | £2,050 | £252,050 | £252,400 |
| 2 | £2,050 | £254,100 | £254,450 |
| 3 | £2,050 | £256,150 | £256,500 |
| 4 | £2,050 | £258,200 | £258,550 |
| 5 | £2,050 | £260,250 | £260,600 |
| 6 | £2,050 | £262,300 | £262,650 |
| 7 | £2,050 | £264,350 | £264,700 |
| 8 | £2,050 | £266,400 | £266,750 |
| 9 | £2,050 | £268,450 | £268,800 |
| 10 | £2,050 | £270,500 | £270,850 |
| 11 | £2,050 | £272,550 | £272,900 |
| 12 | £2,050 | £274,600 | £274,950 |
Indicative only, for deal screening - not an offer or a lending decision. Rates band by LTV, term and property type. Interest is charged on the loan amount at the headline monthly rate; the total is the same whichever structure you pick, only the cashflow differs. Third-party fees are estimates and vary by property and solicitor.
Monthly rates on Sandwell files, year by year
The single 2024 file priced at 0.79% a month. The four 2026 files ran from 1.02% to 1.16%.
| Funded | Files | Lowest rate pm | Highest rate pm |
|---|---|---|---|
| 2024 | 1 | 0.79% | 0.79% |
| 2025 | 1 | 1.05% | 1.05% |
| 2026 | 4 | 1.02% | 1.16% |
Our rates start from 0.75% pm, which is rarely achieved. None of the Sandwell files reached it. Based on Lendlord aggregated data.
Sandwell sale prices by district
HM Land Registry median price paid, September 2025 to August 2026, in the districts where we lent.
| District | Our deals | Sales registered | Median price paid |
|---|---|---|---|
| WS10 | 2 | 148 | £225,000 |
| All Sandwell | 6 | 1,906 | £225,000 |
Standard sales only, from HM Land Registry under the Open Government Licence. Recent months under-count while sales register. ONS puts the Sandwell average rent at £953 a month in August 2026, 8.0% higher than a year before.
West Bromwich rents on Lendlord landlords' homes
There is no Sandwell-wide cut yet. These are 23 let West Bromwich homes owned by Lendlord landlords, next to the regional figure. Snapshot at 30 September 2026.
| Figure | West Bromwich |
|---|---|
| Median rent a month | £890 |
| Middle half of rents | £713 to £1,125 |
| Gross yield | 5.5% |
| Median value | £200,000 |
| Share with a mortgage | 58% |
| Homes counted | 23 let, 24 owned |
Rents as recorded on each let home. Values are owner estimates. Middle half: the 25th to 75th percentile. Source: pooled Lendlord records.
A median West Bromwich let earns £890 a month, against an ONS Sandwell average of £953.
At 145% cover on a 5.5% stress rate, £890 supports about £134,000. A 75% loan on a £200,000 home would be £150,000, so rent sets the remortgage here. Only 23 lets sit behind these figures, so test your own rent.
Sandwell EPC ratings
We counted 79,371 home energy certificates lodged in Sandwell over October 2016 to October 2026. Band D alone holds 40.3%.
- Band A
Share of certificates: 0.3% (243)
- Band B
Share of certificates: 7.3% (5,764)
- Band C
Share of certificates: 42.5% (33,727)
- Band D
Share of certificates: 40.3% (32,004)
- Band E
Share of certificates: 7.8% (6,227)
- Band F
Share of certificates: 1.3% (1,017)
- Band G
Share of certificates: 0.5% (389)
What the Sandwell bridges paid for
Auction lots dominate here: 5 of 6 files, with one buy-to-let purchase. Each line below counts our local files of that type and links the full guide.
- Auction bridging (5 files)
- Bridging for a rental purchase (1 file)
- Unmortgageable property (4 files)
Black Country auction rooms
Most Sandwell lots go through Birmingham-based sales. Dates checked 7 October 2026.
Bond Wolfe
Birmingham, Black Country lots. Next sales: 22 October 2026 and 9 December 2026.
Auction House Birmingham and Black Country
Covers West Bromwich and Sandwell.
Confirm dates and fees with the auctioneer. We are not linked to any house listed.
From a Black Country sale room to funds in four steps
Our current process can fund from 5 days. The Sandwell files took 12 to 137 days from application to funds.
- Upload once. AI reads your ID, bank statements and company papers in minutes, with identity, sanctions and fraud checks run alongside.
- Exit tested up front. Underwriting stress-tests the remortgage or the sale before we issue terms.
- A single solicitor. Dual representation puts one firm on both sides, so questions on the coal search get one answer.
- Papers on cue. Loan documents are generated as soon as the offer conditions are met.
A mining search ordered late is one delay you can remove. Bring the CON29M, the legal pack and the works quote with the application.
Bridging finance explained: how a bridge funds a lot before the mortgage
In a TikTok post comparing bridging with mortgages, the BTL Broker channel walked through the process under this heading:
…From application to completion: understanding Lendlord’s tech-driven bridging journey…
Related bridging pages
Our Birmingham bridging page covers the city next door. For lots that fail a mortgage valuation, see bridging for unmortgageable homes. We also wrote up what happens with no kitchen.
What borrowers say about working with Lendlord
Three reviews from Trustpilot, from customers across the UK.
Simmy and her team did a terrific job…
“Simmy and her team did a terrific job for us as ever, and would highly recommend as professional, thorough and charming to work with.”
Oliver Gooch
Verified review on Trustpilot from Oliver GoochLendlord is my go to place for everything mortgage related
“Lendlord is my go to place for mortgages and re-mortgages alike. They have made the process so smooth, efficient, and painless. I have never come across another company that makes everything feel so easy…”
shaz
Verified review on Trustpilot from shazSimranpreet Kaur is a very helpful…
“Simranpreet Kaur is a very helpful adviser. She is hardworking and eager to help. I have also had a positive experience and positive outcome. I would highly recommend Simranpreet Kaur. She is a Gem to work with considering I have have several mortgage advisers in the past.”
HELEN
Verified review on Trustpilot from HELEN
Sandwell bridging FAQ
Will you lend on a Sandwell house with no kitchen?
Yes, that is most of our Sandwell book. 4 of 6 deals had no working kitchen or water at funding.
Do I need an HMO licence in Sandwell?
If three or more people from two or more households share, yes. The additional licensing scheme covers the whole borough until 30 September 2029. See the Sandwell additional licensing page.
Why are your Sandwell figures West Midlands figures?
Sandwell has 6 deals, under the 10-deal bar for a median. The counts on this page are the Sandwell files.
Further reading for works-first lots in the Black Country
Most of our Sandwell lots could not take a mortgage on the day of the sale. These pages cover the finance, the exit and the checks behind that kind of buy.
- Finance for a home lenders will not mortgage: The position of 4 of our 6 local files.
- Bridging a house with no working kitchen: What the valuer and the exit need to see.
- 2026 bridging rates by loan type: Compare with the Sandwell rate table above.
- Birmingham files across the borough boundary: The neighbouring city page.
- Work out the buy-to-let numbers: Rent cover for the remortgage exit.
- How we count and check deal figures: The rules behind every number here.
Clare Harris
Bridging Loan Specialist and Director of Growth at Lendlord · 12+ years in loans and lending · Reviewed the 6 Sandwell files and the West Midlands cut
Last reviewed
Where the Sandwell numbers come from
Sandwell has 6 deals in the 272 disclosed deals, funded February 2024 to April 2026. That is under the 10-deal bar for a median.
The table and the two cases are Sandwell deals. Loans are rounded down to £5,000. A district that appears once is marked Not shown.
Got a Sandwell lot that needs work?
Tell us the guide price and the works list. We will say how we would structure the bridge and what the exit needs.
Who provides the service
Lendlord Limited, company 11973095, runs the landlord software. The registered office is Churchill House, 137-139 Brent Street, London, NW4 4DJ. The public name is Lendlord.
Lendlord Finance Limited, company 13696524, uses the trading name Lendlord Capital for bridging. It lends that loan itself. Mortgage and remortgage applications are a separate service.
Lendlord Finance Limited arranges those mortgages as an appointed representative of Windfall Limited. The FCA authorises Windfall Limited under firm reference 225908. The mortgage itself comes from a lender on that panel.
Lendlord Limited is registered for account information services, so a bank feed can be read with your consent. That registration is not permission to lend, and it is not permission to arrange a mortgage.
Bridging on this page is secured on property in England and Wales. Lending here goes up to 80% LTV. A below-market buy can still reach 90% of the purchase price.